Executive Overview
The landscape of digital travel discovery within the European Union has undergone a fundamental structural transformation. In response to relentless, multi-year antitrust scrutiny and sweeping regulatory mandates enforced by the European Commission, Google has officially deployed a deeply overhauled search results architecture tailored specifically for users across the continent.
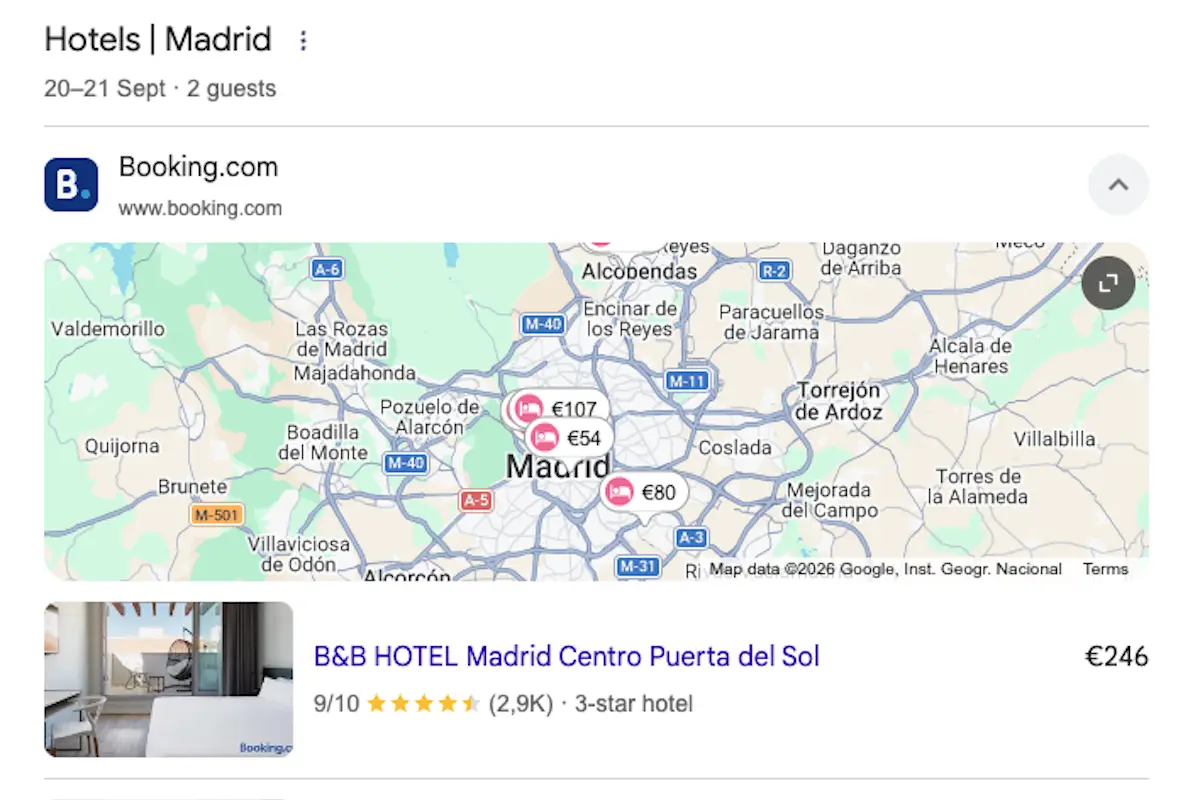
At the center of this update are distinct, newly engineered visual blocks dedicated to flights, hotels, and dining queries. When European consumers initiate a travel-related search—such as looking for accommodation in Madrid or cross-border flights—they are no longer met with the monolithic, Google-dominated SERP (Search Engine Results Page) features of the past. Instead, Google has divided the layout into two distinct interface units: the “aggregator unit,” which showcases intermediaries like online travel agencies (OTAs) such as Booking.com and Agoda, and the “supplier unit,” which elevates direct providers, including individual hotel properties and commercial airlines.
This high-stakes adjustment is not merely a cosmetic redesign; it is a direct concession to the European Union’s Digital Markets Act (DMA) and prior landmark antitrust decisions that penalized Google for self-preferencing its own vertical travel products (such as Google Flights and Google Hotels) at the direct expense of competing aggregators and independent suppliers. By creating dedicated spaces for third-party platforms with expandable listings, Google is attempting to walk a regulatory tightrope: complying with strict European competition laws while preserving its status as the indispensable gateway to the global travel ecosystem.
For travel executives, hoteliers, digital marketers, and competition watchdogs, this shift marks the dawn of a new era in search engine optimization (SEO), performance marketing, and digital distribution economics.
Detailed Chronology: The Path to the EU Interface Overhaul
To understand the weight of Google’s latest European rollout, one must trace the regulatory battlegrounds and iterative enforcement actions that forced the tech giant’s hand over the past decade.
1. The Genesis of Search Neutrality Probes (2010–2017)
The friction between Google and European regulators began in earnest in the early 2010s, when smaller comparison-shopping engines, travel platforms, and vertical search operators filed formal complaints with the European Commission (EC). Competitors alleged that Google was systematically abusing its dominant market share in general search to favor its own specialized search services.
After years of preliminary inquiries, the EC issued a landmark statement of objections in 2015, culminating in a historic €2.42 billion fine handed down in June 2017. The Commission ruled that Google had illegally abused its dominance by giving its own comparison-shopping service an illegal advantage in search results, forcing rival services down the page or omitting them altogether. While that specific case initially targeted shopping, it established a terrifying legal precedent for Google’s other specialized verticals, including Google Flights and Google Hotels.
2. The Search Display Remedies and "Consent" Iterations (2018–2022)
In the wake of the shopping penalty, Google was compelled to submit compliance proposals. The company introduced auction-based models for its shopping unit, allowing rivals to bid for placement alongside Google’s own service. However, competitors and trade associations continuously argued that these remedies were insufficient and that Google’s user interfaces still tilted the playing field in its favor.
Concurrently, European regulators shifted their focus toward broader legislative frameworks. The drafting and ultimate passage of the Digital Markets Act (DMA)—designed to rein in "gatekeeper" platforms—signaled that piecemeal antitrust fines were no longer considered adequate by Brussels. Platforms designated as gatekeepers would face proactive, prescriptive rules dictating how they must design their interfaces and handle third-party data.
3. The Digital Markets Act Compliance Deadline and Travel-Specific Probes (2023–Early 2024)
By 2023, the European Commission intensified its scrutiny specifically targeting travel and local search features. Regulators questioned whether Google’s prominent integration of map packs, hotel carousels, and flight booking widgets violated the DMA’s core prohibition against self-preferencing. Under the DMA, gatekeepers are explicitly barred from treating their own services and products more favorably in ranking and user interface design than those of similar third parties.
Google realized that minor adjustments would no longer satisfy the European Commission’s executive vice-president in charge of competition, Margrethe Vestager. The company needed a structural, algorithmic, and visual overhaul of its travel search infrastructure for all EU member states.
4. The 2024 European Rollout
This week’s deployment represents the culmination of these pressures. By rolling out the "aggregator" and "supplier" units across EU member states, Google has formally implemented a bifurcated search architecture. Initiated silently and tested through various iterations, the live rollout for queries like Madrid hotels confirms that Google is systematically reshaping how European travelers interact with digital travel inventory.
Supporting Context & Metrics: The Stakes for the Travel Industry
The economic implications of Google’s search engine real estate are staggering. Billions of dollars in gross bookings rely on the visibility afforded by Google’s top-of-funnel traffic. To gauge the gravity of this interface update, one must examine the dynamics of online travel distribution, search market share, and consumer behavior metrics within the European Union.
The Anatomy of the New Interface
Under the newly minted European layout, a user searching for travel services encounters two distinct visual zones:
- The Aggregator Unit: This module houses intermediary platforms—predominantly Online Travel Agencies (OTAs) such as Booking.com, Expedia, Agoda, and Trip.com, alongside meta-search engines. Notably, the top-ranked provider within this stack has its results expanded by default, drawing immediate user attention. When a user interacts with the stack, they are presented with a clean, comparative view of rates across multiple third-party channels.
- The Supplier Unit: Operating in tandem or adjacent to the aggregator unit, this block is dedicated strictly to direct providers. For hospitality queries, this means individual hotels, boutique properties, and global hotel chains (e.g., Marriott, Accor, Hilton). For aviation queries, it displays direct airline booking channels (e.g., Lufthansa, Air France-KLM, Ryanair).
Market Dominance and Traffic Distribution
Google’s search engine market share in Europe consistently hovers above 90%, dwarfing competitors like Bing, DuckDuckGo, and specialized platforms in general query volume. Because Google serves as the primary "tollbooth" for the internet, any alteration to its SERP layout carries profound downstream effects on customer acquisition costs (CAC) for travel brands.
| Feature / Metric | Pre-Update European SERP | Post-Update European SERP (DMA Compliant) |
|---|---|---|
| Primary Focus | Unified Google Flights/Hotels widgets & Google ads | Split architecture: Aggregator Unit & Supplier Unit |
| Third-Party Visibility | Integrated via paid ads and organic carousels | Dedicated "Aggregator Stack" with expanded top results |
| Direct Supplier Visibility | Mixed within standard listings and map packs | Dedicated "Supplier Unit" for brand-direct inventory |
| Regulatory Standing | High risk of EU non-compliance penalties | Designed to meet DMA self-preferencing restrictions |
Consumer Impact and Behavioral Shifts
Early usability observations from the EU indicate that European consumers are navigating a denser, more text-and-link-heavy search results page. While Google’s own native widgets have historically kept users within Google’s walled garden (allowing them to book or research without leaving the search environment), the new aggregator and supplier units actively push users outward toward third-party domains and direct supplier sites.
For hoteliers and independent travel brands, this restructuring introduces a double-edged sword:
- The Opportunity: Direct suppliers now have a designated structural space—the supplier unit—that mitigates the risk of being completely obscured by massive OTA ad spend or Google’s native comparison tools.
- The Challenge: The visual complexity of the SERP increases cognitive load for consumers. If users become fatigued by navigating stacked aggregator lists and supplier blocks, the top-ranking aggregator (which is expanded by default) stands to capture an outsized share of initial click-through traffic.
Official Statements and Industry Reactions
The rollout of Google’s European travel search changes has triggered intense commentary from regulatory bodies, travel industry trade associations, and corporate executives.
The European Commission’s Stance
While the European Commission has not yet issued a final, formal endorsement of the new UI—maintaining a vigilant stance to monitor actual market behavior—spokespersons have repeatedly emphasized that compliance with the Digital Markets Act is continuous, not a one-time event.
An EU regulatory insider noted:
"We welcome steps taken by designated gatekeepers to open their ecosystems and ensure fair, transparent, and non-discriminatory treatment of third-party competitors. However, our technical teams and economic experts will closely monitor how these interfaces perform in practice. If the architecture subtly continues to favor Google’s proprietary services or creates unfair bottlenecks, enforcement actions will follow swiftly."
Google’s Perspective
Google has consistently defended its product evolution, arguing that its search innovations are designed to provide maximum utility, choice, and transparency to European consumers while adapting to complex, shifting legal frameworks.
In a statement addressing recent updates across its European services, a Google spokesperson highlighted the engineering challenges involved:
"We have engaged in extensive, constructive dialogues with the European Commission and industry stakeholders. Our goal has always been to connect people with the most helpful, relevant information while complying fully with our obligations under European law. These interface updates reflect our ongoing commitment to providing clarity, fostering competition, and giving both large and small travel providers fair visibility on our results pages."
Reaction from Online Travel Agencies (OTAs) and Industry Coalitions
The reaction from Europe’s powerful travel coalitions, including the European Technology and Travel Services Association (ETTSA) and major OTA executives, has been cautiously optimistic yet intensely analytical.
For years, OTAs argued that Google’s prime real estate monopoly starved them of organic traffic, forcing them to spend billions on Google Ads simply to remain visible for core travel queries. The mandatory creation of an "aggregator unit" is viewed by these platforms as a structural victory, though questions remain regarding how ranking algorithms within the stack will operate.
"For over a decade, comparison platforms and travel intermediaries have fought for a level playing field in digital search," said a senior representative from a major European travel distribution advocacy group. "The implementation of distinct aggregator and supplier units is a step in the right direction. However, the devil is always in the algorithmic details. We will be measuring conversion rates, click distributions, and visibility metrics very closely to ensure that this is genuine remediation rather than compliance theater."
Hoteliers, meanwhile, have expressed relief at the formal introduction of the "supplier unit," viewing it as a long-overdue mechanism to help drive direct bookings and reduce high commission payouts to third-party distribution channels.
Future Outlook: What the EU Overhaul Means for Global Travel
As Google embeds these changes across European member states, industry analysts are looking ahead to predict how this regulatory shockwave will ripple across global markets, shape technological roadmaps, and alter digital marketing strategies.
1. Will the EU Model Go Global?
One of the most pressing questions in the tech and travel sectors is whether Google will export its EU-style search interface to other major jurisdictions, such as the United States, the United Kingdom, and the Asia-Pacific region.
While antitrust pressure in the U.S. is mounting—highlighted by the Department of Justice’s ongoing antitrust lawsuits against Google—U.S. regulatory frameworks lack the explicit, proactive mandates found in Europe’s Digital Markets Act. Nevertheless, multinational tech companies often find maintaining bifurcated codebases and user interfaces operationally burdensome. If the European UI proves successful at satisfying regulators without fundamentally crippling user engagement, Google may gradually adopt elements of the aggregator/supplier split globally to streamline its product architecture.
2. The Evolution of Travel SEO and Performance Marketing
For digital marketers in the travel sector, the rulebook is being rewritten. Traditional SEO strategies focused purely on securing a top organic rank or optimizing for a single Google widget must now account for dual-unit visibility.
- Aggregator SEO: OTAs and meta-search engines must fiercely optimize their positioning to capture the coveted "expanded by default" top spot within the aggregator stack. Winning this position will require a blend of strong brand equity, competitive pricing data feeds, and optimized structured data.
- Supplier SEO & Direct-to-Consumer Strategy: Independent hotels, regional chains, and airlines must invest heavily in ensuring their direct inventory feeds are fully optimized for the "supplier unit." Failing to integrate cleanly with Google’s direct supplier protocols could mean total invisibility in this dedicated zone, leaving brands entirely at the mercy of OTA commissions.
3. Artificial Intelligence and the Next Generation of Search
Compounding the regulatory shift is the rapid integration of Generative AI into search experiences, such as Google’s AI Overviews (formerly Search Generative Experience). As conversational AI begins to curate complex travel itineraries—synthesizing flights, hotels, and local activities into a single chat interface—the traditional concept of "aggregator" and "supplier" units will face new evolutionary pressures.
Regulators will inevitably scrutinize how AI-generated travel summaries rank and recommend suppliers, ensuring that generative models do not bypass the spirit of the DMA by quietly favoring proprietary Google travel data within conversational responses.
4. Conclusion
Google’s latest European travel search overhaul represents a watershed moment in the uneasy marriage between big tech dominance and regulatory governance. By splitting its results page into dedicated aggregator and supplier units for European users, Google has bowed to the formidable reality of the European Union’s antitrust enforcement.
Yet, the true test of this interface update will not be found in its visual layout, but in its economic outcome: Will it successfully restore a competitive, level playing field for Europe’s vast ecosystem of travel providers, or will the gatekeeper simply find new ways to adapt its algorithms within the lines of the law? For the global travel industry, the transformation of digital search has only just begun.