
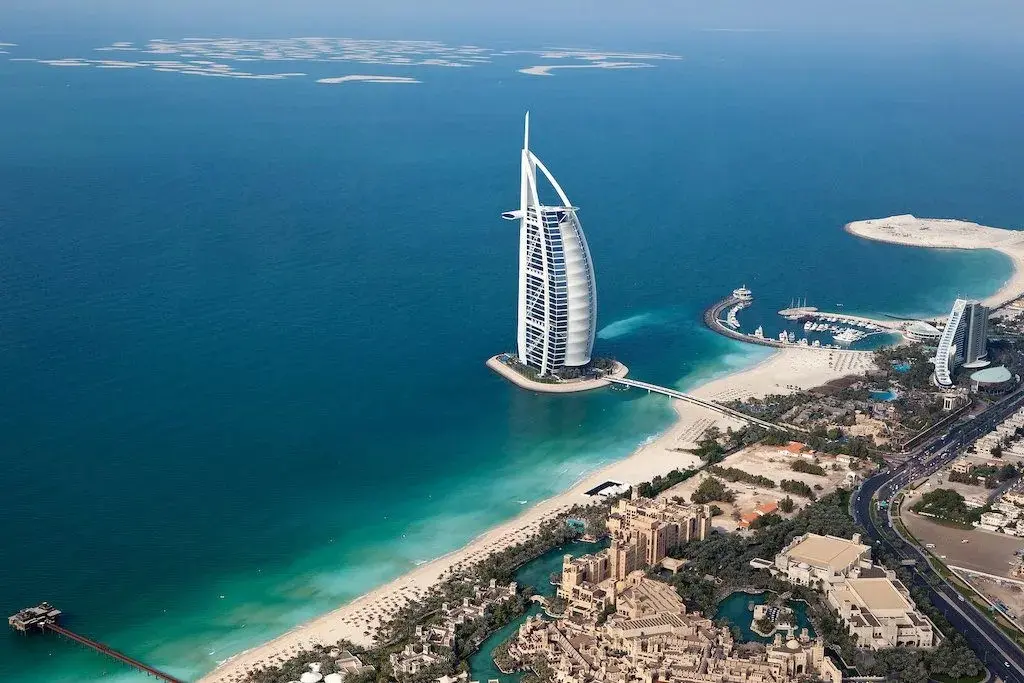
DUBAI — At the bustling exhibition halls of the Dubai World Trade Centre during this week’s Arabian Travel Market (ATM), industry titans, regional developers, and multinational hospitality executives gathered under a cloud of cautious optimism. While the immediate post-pandemic turbulence has given way to surging foot traffic and packed exhibition booths, a quiet consensus has emerged among the region’s elite hoteliers: the finish line for a comprehensive, structural market recovery has been pushed back.
According to leadership figures across the Gulf Cooperation Council (GCC) hospitality sector, full economic and volumetric stabilization across key source markets will not materialize this year, nor the next. Instead, industry veterans are projecting a delayed horizon, pinning hopes on the second quarter of 2027 for a true, uncompromised return to pre-crisis equilibrium.
Beneath the surface of resilient headline occupancy figures lies a more complex narrative. Hoteliers across the United Arab Emirates and the wider Middle East are grappling with a persistent structural imbalance: occupancy metrics are rebounding at a pace that vastly outstrips average daily rates (ADR). This widening gap between heads-in-beds and pricing power, compounded by geopolitical frictions, travel advisories, and lingering macroeconomic headwinds in Western source markets, is redefining what recovery looks like in one of the world’s most dynamic tourism corridors.
Executive Overview: The 2027 Horizon
The sentiment at ATM Dubai marks a significant recalibration of expectations. As recently as late 2023, optimistic projections pointed toward a broad-based normalization of international tourism flows by the close of 2025 or early 2026. However, executive briefings and panel discussions this week paint a different picture.
The recovery trajectory is no longer viewed as a sharp V-shaped rebound, but rather as a protracted, uneven ascent. Victor Abou-Ghanem, CEO of Story Hospitality—operator of prominent regional properties including the H Hotel Dubai and the luxury Al Maya Island & Resort in Abu Dhabi—offered a sobering assessment during the event.
"We expect a full recovery of travel volumes from Europe and the U.S. in the second quarter of 2027," Abou-Ghanem stated. "A recovery in Q4 this year is simply too soon."
This sentiment was echoed across boardrooms. The primary driver delaying full recovery is not a single catastrophic event, but a cumulative friction. Hoteliers report that while regional travelers and domestic staycation markets have provided a reliable baseline, the high-spending long-haul segments from Europe and North America are recalibrating their travel habits. Economic pressures in core Western economies, combined with a persistent lag in corporate travel budgets and regional security perceptions, have created a protracted plateau.
Consequently, the industry is entering a transitional era. To safeguard asset values and maintain market share, operators are being forced to rethink their distribution strategies, pivot toward emerging feeder markets in Asia and the subcontinent, and accept that volume will temporarily substitute for yield.
Detailed Chronology: From Pandemic Rebound to the 2027 Realignment
To understand how the Middle Eastern hospitality sector arrived at this projected 2027 benchmark, it is essential to trace the arc of the region’s post-2020 transformation.
Phase 1: The Accelerated Rebound (2021–2022)
When global borders began reopening, the Middle East—and Dubai in particular—positioned itself as an agile haven for international travelers. Aggressive vaccination campaigns, lenient entry requirements, and a swift economic reopening allowed the UAE to capture displaced global tourism. During this window, hoteliers enjoyed unprecedented pricing power. Pent-up demand from affluent travelers fueled record-breaking ADRs and RevPAR (Revenue Per Available Room) metrics, creating an illusion of permanent hyper-inflationary growth.
Phase 2: The Normalization Squeeze (2023–2024)
As competing international destinations—particularly across Europe and Asia—fully reopened their borders, the geographic monopoly held by the Middle East began to dissolve. Long-haul travelers diversified their itineraries once more. During this period, hotel supply across the GCC expanded rapidly, with thousands of new keys entering the pipeline. The influx of inventory, paired with normalizing demand, triggered the first signs of structural strain. Occupancy rates remained stable, but hoteliers found themselves unable to sustain the stratospheric room rates of the immediate post-pandemic years without sacrificing volume.
Phase 3: Geopolitical Friction and Economic Headwinds (2024–2025)
The escalation of geopolitical tensions in the wider Middle East introduced a new layer of complexity. While the UAE and neighboring GCC nations remained remarkably secure and insulated from direct disruptions, international perceptions were inevitably impacted. Travel advisories issued by Western governments, while often generalized, created psychological barriers for risk-averse leisure travelers and corporate risk management departments. Simultaneously, persistent inflationary pressures and high interest rates in the United Kingdom, the Eurozone, and the United States eroded disposable incomes and dampened corporate travel expenditure.
Phase 4: The Strategic Adjustment Toward 2027
Today, the industry has entered a phase of realistic stabilization. Hoteliers are no longer chasing the ghost of 2021–2022 pricing anomalies. Instead, executive planning has shifted toward long-term asset optimization, operational efficiency, and a measured glide path toward the target date of Q4 2027—the milestone identified by major institutional operators as the true baseline for structural recovery.
Supporting Context & Metrics: The Occupancy-Rate Disconnect
The core analytical insight emerging from the Arabian Travel Market is the phenomenon of recovery bifurcation: occupancy is returning significantly faster than average daily rates.
In traditional hospitality cycles, a surge in occupancy is closely followed by an upward adjustment in pricing. However, the current cycle in the Middle East has decoupled these two key performance indicators.
The Mechanics of the Gap
- Supply Influx: Over the past three years, the GCC has witnessed a historic construction boom. Major urban centers like Dubai, Riyadh, Doha, and emerging tourism hubs like Ras Al Khaimah have added substantial inventory across all tiers, from budget-lifestyle hotels to ultra-luxury resorts.
- Competitive Compression: To absorb this new inventory and maintain baseline cash flows, operators have engaged in tactical discounting. While heads are in beds—evidenced by healthy occupancy figures hovering in the high 70s and low 80s percentiles across prime markets—the yield per room has compressed.
- The Yield-Volume Trade-Off: Corporate clients and tour operators, facing their own budgetary constraints, have resisted rate hikes. Consequently, hoteliers are forced to accept lower margins to keep properties operational and staff utilized.
Regional Nuances
The recovery timeline varies significantly by geography and asset class:
- Urban Business Hubs (Dubai, Doha, Riyadh): Benefiting from a robust calendar of international MICE (Meetings, Incentives, Conferences, and Exhibitions) events, corporate travel is steadily returning, though extended booking windows remain elusive.
- Leisure-Centric and Emerging Destinations (Ras Al Khaimah, Abu Dhabi, Oman): Heavily reliant on European leisure segments, these markets face a more protracted recovery curve due to the lingering impact of long-haul flight costs and travel advisories.
Official Statements: Industry Leaders Weigh In
The discussions at ATM Dubai highlighted a unified realization among executives: managing stakeholder expectations is now as critical as managing property operations.
Phillipa Harrison, CEO, Ras Al Khaimah Tourism Development Authority (RAKTDA)
Offering a granular view of regional feeder markets, Phillipa Harrison emphasized that while proximity markets have stabilized, distant international source markets require a much longer runway.
"Some neighboring markets will be back by Q1," Harrison noted in an exclusive briefing with Skift. "Other markets like Germany might not be back until Q4 next year. That last 10 to 15 percent takes a little while to come back. And advisories don’t help either."
Harrison’s comments underscore the vulnerability of emerging leisure destinations to external bureaucratic interventions. Travel advisories issued by Western foreign offices, while sometimes disproportionate to ground realities in the GCC, exert an outsized psychological influence on risk-averse travelers, delaying booking conversions for luxury and mid-market resorts alike.
Saurabh Tiwari, Vice President, Indian Hotels Company Limited (IHCL)
Reinforcing the timeline for macroeconomic stabilization, Saurabh Tiwari of IHCL pointed out that operational normalcy across all metrics cannot be prematurely forced.
"Though the recovery has started, business won’t revert to 2024–2025 levels until Q4 2027," Tiwari explained, highlighting that operational planners must build medium-term strategies that account for sustained margin management rather than expecting sudden market corrections.
Future Outlook: Navigating the Road to 2027
As the Middle Eastern hospitality sector charts its course through the remainder of the decade, success will depend on strategic adaptability, technological integration, and disciplined asset management.
1. Diversification of Feeder Markets
To offset the sluggish return of traditional Western European and North American segments, hotel operators are aggressively pivoting toward high-growth Asian markets—most notably India and China—alongside the Commonwealth of Independent States (CIS) and domestic GCC travelers. India, in particular, has emerged as a powerhouse for both leisure and MICE tourism, boasting strong airlift connectivity and cultural affinity with the region.
2. Technological Integration and Revenue Management
With the occupancy-rate gap pressuring margins, hoteliers are investing heavily in advanced revenue management systems (RMS) powered by artificial intelligence. These tools enable dynamic pricing models that optimize yield in real-time, helping operators extract maximum value from every available room without relying on blunt-instrument discounting.
3. Sustainability as a Competitive Advantage
As institutional investors and conscious travelers increasingly prioritize environmental, social, and governance (ESG) credentials, Middle Eastern properties are accelerating sustainability initiatives. From water conservation technologies to zero-waste culinary programs, aligning with global green standards is no longer optional; it is a vital differentiator in capturing corporate accounts and eco-conscious leisure travelers.
Conclusion
The narrative emerging from the Arabian Travel Market is one of pragmatic resilience. While the headline figures may not yet reflect the runaway boom years of the immediate post-pandemic era, the Middle East remains one of the most dynamic and robust hospitality landscapes in the world. By acknowledging that full structural recovery—particularly the reconciliation of occupancy and rate—requires patience out to 2027, industry leaders are laying the groundwork for sustainable, long-term growth. The journey may be longer than initially anticipated, but the destination promises a more mature, balanced, and resilient regional tourism economy.