
Executive Overview
The global transition of freight transportation away from fossil fuels and toward electricity is no longer a matter of if, but how and when. Plummeting battery costs, driven by manufacturing scale and chemical innovations, are universally lowering the entry barrier for zero-emission logistics. Yet, logistics does not exist in a vacuum. Freight networks are massive, highly entrenched physical systems anchored to geography, historical investments, and unique economic landscapes.
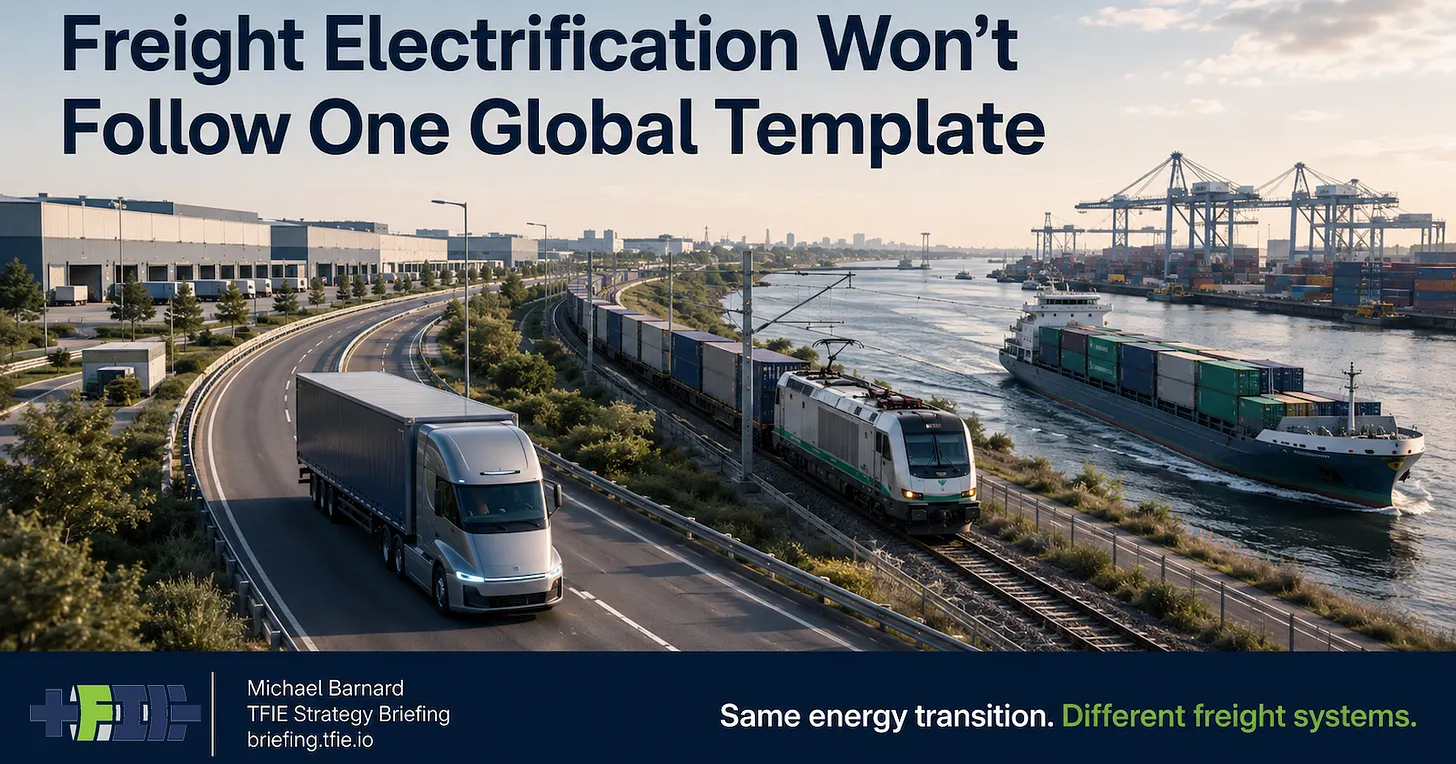
While the cost of energy storage is falling along a common global curve, the path toward total freight electrification will not follow a single, standardized blueprint. China, India, Europe, and the United States are approaching this transition from vastly different starting points. These differences are defined by their "modal split"—the historical distribution of freight carried across road, rail, and water systems.
Inherited infrastructure dictates where electricity must enter the system. Whether a nation relies primarily on massive trucking corridors, high-capacity electrified rail grids, or extensive inland waterways alters the economics of capital allocation. Consequently, the global green logistics revolution is fracturing into regional adaptations. Battery costs may be global, but freight geography is resolutely local.
Detailed Chronology: Milestones in Global Freight Electrification
To understand where the logistics sector is heading through the 2030s, it is crucial to examine the timeline of policy pushes, infrastructure milestones, and technological shifts that have brought major economies to their current crossroads.
- Pre-2020: The Foundation of Modal Splits
Decades of capital investment cement regional logistics preferences. Europe expands its rail networks but steadily loses inland freight market share to road transport. China constructs massive industrial arteries combining roads, high-speed and conventional rail, and river networks. The U.S. relies heavily on a privately owned, long-haul diesel rail network alongside an expansive interstate trucking system. - 2020–2023: The Battery Cost Inflection and Policy Mobilization
As lithium-ion pack prices continue a long-term downward trajectory, governments worldwide begin introducing aggressive zero-emission vehicle (ZEV) mandates. India accelerates its Dedicated Freight Corridor (DFC) project, laying the groundwork for heavy-haul, electrified rail transport. China initiates aggressive municipal and national pilots for electric heavy-duty trucks (HDTs), utilizing battery-swapping models to mitigate range anxiety and downtime. - 2024–2025: Diverging Regional Realities
- Europe: Electrically chargeable trucks (above 3.5 tonnes) reach 4.2% of total EU registrations by 2025, signaling the slow start of a massive road-fleet transition. Simultaneously, road transport continues to capture inland freight share, pulling away from the continent’s extensive 200,000-kilometer rail grid.
- China: Sales of "new-energy" heavy trucks surge to industrial scale, setting the stage for an explosive growth curve.
- United States: National Renewable Energy Laboratory (NREL) modeling highlights a clear trajectory: zero-emission trucks are projected to achieve total-cost-of-driving (TCO) parity across major market segments by 2035.
- Early 2026: Industrial-Scale Execution
- China records roughly 140,000 new-energy heavy truck sales in the first half of the year alone—a staggering 78.6% year-over-year increase.
- India’s completed Dedicated Freight Corridors handle roughly 480 freight trains per day, proving the viability of high-capacity, electrified rail logistics.
- 2030 and Beyond: The Target Horizon
China aims for new-energy heavy trucks to account for approximately 40% of its annual heavy-truck sales by 2030. Meanwhile, North American and European logistics operators race against tightening carbon regulations, trying to balance the electrification of relentless road freight with the modernization of legacy rail corridors.
Supporting Context & Metrics: The Modal Split Breakdown
To comprehend why a universal electrification playbook fails, one must analyze how different superpowers move domestic cargo. The modal split—the percentage breakdown of freight work (tonne-kilometers) handled by road, rail, and water—forms the baseline of every nation’s transition economics.
Comparative National Freight Modal Splits
| Country / Region | Road Freight Share | Rail Freight Share | Water (Inland/Domestic) Share | Confidence Level |
|---|---|---|---|---|
| China (2025 Est.) | ~44% | ~20% | ~36% | High (Harmonized Data) |
| European Union (EU-27) | ~54% | ~12% | ~34% | Moderate (Recombined Datasets) |
| India (NITI Aayog Baseline) | ~69% | ~23% | ~8% | High (Policy Modeling Base) |
| United States (Reconstructed) | ~53% | ~36% | ~10% | Lower Confidence (Derived Estimates) |
1. China: The Balanced Triad
China boasts the most balanced and voluminous freight ecosystem among major economies. With roughly 44% road, 20% rail, and 36% domestic water freight, Beijing possesses the luxury of multi-modal optimization. It can aggressively electrify an enormous truck fleet while simultaneously moving staggering volumes of bulk materials via its rivers and electrified rail lines.
2. The European Union: Road Dominance Despite Rail Density
The EU-27 reflects a heavy reliance on road transport at roughly 54%, supplemented by 34% internal water freight and just 12% rail. This occurs despite Europe housing over 200,000 kilometers of railway infrastructure. Data from 2014 to 2024 reveals a telling trend: road freight actually gained about 3.3 percentage points of inland freight share during the decade. Europe cannot rely on rail alone; it must tackle road emissions head-on.
3. India: High Road Reliance and Dedicated Rail Corridors
According to NITI Aayog modeling baselines, India’s logistics are exceptionally road-heavy, standing at approximately 69% road, 23% rail, and a modest 8% water freight. This heavy reliance on asphalt makes road fleet decarbonization an absolute national priority, even as the nation scales up its advanced rail infrastructure.
4. The United States: The Heavy Rail Holdout
A reconstructed U.S. comparison places the freight split at roughly 53% road, 36% rail, and 10% water. While road transport dominates short-to-medium hauls, the U.S. commercial rail sector remains a massive economic engine, moving heavy, dense cargo over continental distances—though it remains overwhelmingly powered by diesel.
Official Statements and Strategic Insights
Industry analysts, economic modelers, and institutional strategists emphasize that the interaction between falling battery costs and inherited infrastructure requires localized strategic thinking.

Insights derived from comprehensive logistics research, such as the TFIE Strategy Briefing, highlight that capital decisions are entirely dependent on regional asset maturity:
"The modal split is only the starting point. Inherited systems change the economics of electrifying trucks, rail, and water, where the same falling battery-cost curve produces different capital decisions, and what that means through the 2030s."
The operational realities in Asia illustrate how policy and infrastructure align to force the pace of change. In China, the integration of heavy electric trucks is moving from experimental fleets to foundational industrial practice. Industry observers note that while "new energy" classifications encompass more than purely battery-electric vehicles (BEVs)—including fuel cell and hybrid setups—the sheer velocity of adoption is unprecedented.
"China is targeting new-energy heavy trucks at around 40% of annual heavy-truck sales by 2030 while building charging and swapping infrastructure along major freight corridors."
In India, the strategy focuses on maximizing the utility of existing state investments. Rather than attempting to magically shift massive volumes of freight from road to rail via fiat, policymakers are upgrading the physical product itself.
"Electrification by itself does not move cargo from road to rail, but dedicated capacity, heavier axle loads, higher speeds, and more reliable schedules can make an already-electrified railway a more competitive freight product."
Meanwhile, in Western markets, the calculus involves fierce competition between modes. As the National Renewable Energy Laboratory (NREL) points out in its vehicle-class modeling, the total cost of driving for zero-emission commercial trucks is closing in on diesel parity. However, legacy systems like North American freight rail cannot be treated as static entities while the trucking industry rapidly innovates.
Future Outlook: Navigating the 2030s and Beyond
As the global economy moves deeper into the 2030s, the trajectory of freight decarbonization will separate nations capable of synchronized multi-modal transformation from those bogged down by legacy infrastructure bottlenecks.
The Regional Roadmaps
- China’s Integrated Scaling: China is set to maintain its lead in sheer volume deployment. By combining a 40% new-energy heavy truck sales target with expanding battery-swapping networks on major trade routes, China minimizes vehicle downtime while capitalizing on its massive domestic manufacturing capacity. Its balanced use of rail and coastal/inland waterways provides a multi-layered buffer against energy supply shocks.
- India’s Corridor Expansion: With approximately 2,800 kilometers of Dedicated Freight Corridors already operational and handling hundreds of freight trains daily by early 2026, India’s game plan centers on capturing high-density freight loops. By leveraging an almost entirely electrified broad-gauge railway network, India can siphon high-value container traffic off congested highways, reducing the relative emissions intensity of its overall logistics sector.
- Europe’s Dual-Front Battle: Europe faces a complex operational challenge. Because road transport continues to gain inland freight share despite a dense rail network, policymakers and fleet managers cannot rely on modal shift alone. Europe must simultaneously modernize and boost the utilization of its 200,000+ kilometers of rail while deploying charging infrastructure for an expanding class of electric heavy goods vehicles (HGVs).
- The United States Logistics Crossroads: The U.S. faces a long-duration competitive transition. American freight rail retains unbeatable advantages in labor productivity and long-haul fuel efficiency for heavy commodities. Yet, the rapid cost parity of battery-electric trucks threatens to erode rail’s long-standing cost moat for medium-haul logistics. To remain competitive, North American Class I railroads must seriously evaluate battery-electric and catenary locomotive integrations, ensuring that rail does not fall behind an aggressively electrifying road sector.
Conclusion
The overarching direction of the global freight industry is unified: fossil fuels are systematically leaving road, rail, and domestic water transport, making way for wires, high-power chargers, and advanced energy storage systems.
Yet, the mechanics of this transition will remain profoundly decentralized. The financial and operational decisions made by logistics operators over the next decade will be dictated not just by the falling price of a kilowatt-hour of battery storage, but by the concrete, steel, and geography of the tracks, roads, and rivers they inherit. Battery costs are global, but freight geography is destiny.