
Executive Overview
For decades, the mechanics of travel loyalty were simple, proprietary, and closely guarded by the industry incumbents. Airlines operated frequent flyer programs, and major hospitality conglomerates ran tiered loyalty point systems designed to keep consumers locked within their brand ecosystems. If you wanted a meaningful discount or a free night on a hotel stay, you turned to legacy players like Expedia Group, Marriott Bonvoy, or Hilton Honors.
Today, that paradigm has fundamentally shattered.
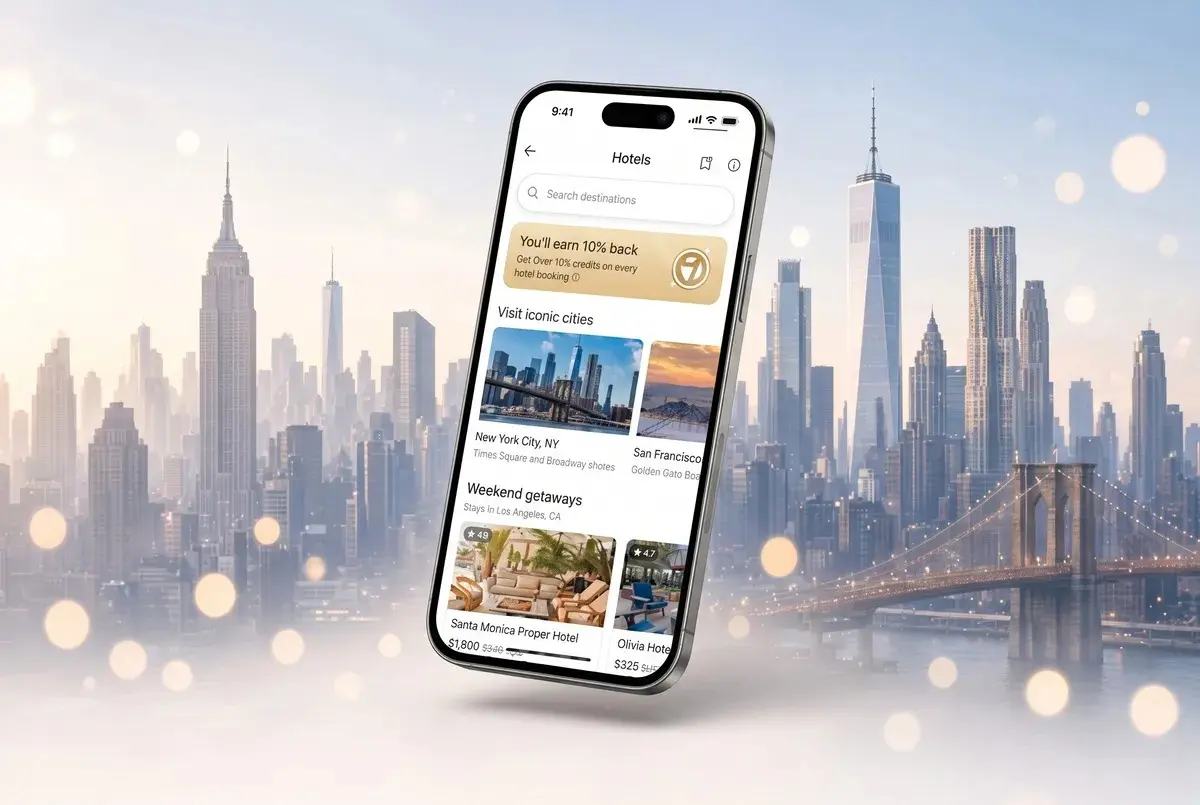
Across the United States, a lucrative 10 percent cash-back or reward incentive on hotel bookings has quietly emerged as the ultimate currency in digital consumer engagement. Yet, paradoxically, the companies offering these aggressive rebates are rarely travel companies at all. Ride-hailing monoliths, financial technology disruptors, and stock-trading apps are now the entities dictating the terms of modern travel commerce.
Take, for instance, the recent partnership announcement between financial services titan Robinhood and London-based travel-technology platform Duffel. By embedding a robust flight, hotel, and car rental booking engine directly inside the Robinhood app for its Platinum and Gold credit cardholders, the trading app has transformed everyday investors into active travel bookers. Platinum cardholders are now rewarded with a staggering 10 percent back on hotels and car rentals, alongside 5 percent on flights.
Robinhood is far from an outlier. Uber lures millions of daily commuters with 10 percent back in ride credits for hotel bookings made through its ecosystem. E-commerce and alternative accommodation giants like Airbnb offer up to 15 percent back on featured hotel inventories.
This deep infiltration of travel booking infrastructure by non-endemic players marks a profound structural shift in the global travel economy. While traditional Online Travel Agencies (OTAs) scale back their baseline rewards programs—exemplified by Expedia’s transition to its OneKey loyalty scheme, which yields a modest 1 percent back on its free Blue tier—outside tech giants are treating hotel bookings as loss-leaders and ecosystem-stickiness drivers. They are funding heavy travel rebates not from hotel margins, but from the massive, highly lucrative financial pipelines of fintech, rideshare, and credit card interchange fees.
The battle for the consumer’s travel wallet is no longer being fought on Expedia or Booking.com. It is being fought in your stock portfolio, your rideshare app, and your digital wallet.
Detailed Chronology: The Evolution of the 10% Travel Rebate
To understand how non-travel tech companies came to dominate the hotel booking incentives landscape, it is essential to trace the historical evolution of travel discounting, from the golden age of legacy OTA loyalty programs to the modern era of embedded finance and API-driven travel tech.
Phase 1: The Incumbent Monopoly (Late 1990s – 2010s)
In the early days of online travel, loyalty was built around the "stamp card" digital equivalent. Hotels.com pioneered one of the most successful retention mechanisms in digital commerce: the "Welcome Rewards" program, later rebranded simply as the Hotels.com rewards scheme. The formula was disarmingly simple yet effective: book ten nights through the platform, and receive a free night calculated as the average value of those ten stays.
Mathematically and psychologically, this equated to roughly a 10 percent return on spend. For nearly two decades, this straightforward rebate was the gold standard for independent travelers who wanted flexibility without being bound to a single hotel chain like Marriott or Hyatt. During this period, travel rewards were almost exclusively owned by companies whose primary revenue derived from travel commissions or lodging markups.
Phase 2: The FinTech Disruption and Ecosystem Locking (2020 – 2024)
As digital wallets matured and consumer expectations shifted toward instant gratification, super-apps began eyeing the travel vertical as a prime arena for cross-vertical monetization. Ride-hailing platforms like Uber realized that users who travel also commute, order food, and book flights. To capture a larger share of consumer wallet spend, Uber launched Uber Travel, integrating flights and hotels directly into its platform.
Simultaneously, financial technology companies—fueled by venture capital and high-interest rate environments—began looking for ways to make their premium credit cards indispensable. Offering high-yield cash back or statement credits on travel became the go-to differentiator in an increasingly crowded premium card market.
Phase 3: The API Infrastructure Revolution (2024 – Present)
The most recent chapter in this transformation is defined by infrastructure-as-a-service providers. Building a native travel booking engine from scratch used to require millions of dollars in engineering overhead, direct contracting with global distribution systems (GDS), and complex customer service operations.
Companies like Duffel shattered these barriers. By offering robust, developer-first APIs, Duffel allowed non-travel tech platforms to plug comprehensive flights, hotels, and car rentals into their existing apps in a matter of weeks. The recent collaboration between Robinhood and Duffel represents the pinnacle of this trend: financial applications can now seamlessly deploy travel rewards programs—such as 10 percent back on hotel bookings—without ever needing to manage a single hotel contract themselves.
Supporting Context & Metrics: Economics of the 10% Back Phenomenon
The economics underpinning the 10 percent hotel rebate model reveal a fascinating financial cross-subsidization strategy. To unpack why a fintech company or a ridesharing platform can afford to hand back 10 percent of a hotel booking value, one must look at where these companies generate their core revenues.
Where the Money Comes From
Traditional OTAs operate on tight margins dictated by hotel commission caps, marketing acquisition costs (particularly Google search ads), and customer acquisition overhead. When an OTA offers a 10 percent reward, it eats directly into the company’s core profitability.
In contrast, non-endemic giants have entirely different P&L (Profit and Loss) structures:
- Credit Card Interchange and Financing Fees: For a company like Robinhood, launching a $695 annual fee credit card backed by high-tier rewards is a play for high-net-worth, high-spending users. Every time a consumer swipes their Robinhood Platinum card, the company collects interchange fees from merchants. Furthermore, margin lending, cash management yields, and subscription fees (such as Robinhood Gold) generate vast cash reserves that easily subsidize promotional travel incentives.
- Customer Lifetime Value (LTV) and Retention: For Uber, a user who books a hotel through their app is significantly less likely to churn to Lyft. The 10 percent ride-credit rebate acts as a closed-loop ecosystem trap: the user gets money back, but that money can only be spent on more Uber rides, keeping the customer locked within the platform’s mobility and delivery network.
- High-Margin Ancillaries: Travel is frequently used as a loss-leader to drive user acquisition for higher-margin digital products. By positioning themselves as lifestyle hubs, these apps capture valuable behavioral data that enhances targeted advertising and premium financial services.
The Decline of Legacy OTA Rewards
While tech interlopers aggressively scale up their rebate programs, legacy OTAs are moving in the opposite direction. Expedia Group’s transition from legacy localized programs to OneKey—which unified Expedia, Hotels.com, and Vrbo under a single currency—resulted in a steep downgrade for casual users.
Under the current OneKey framework, members on the free Blue tier earn a meager 1 percent back on hotels. Even for higher status tiers, matching the ubiquitous 10 percent baseline offered by modern fintech competitors requires substantial, sustained annual spending within the Expedia ecosystem. This strategic retreat by traditional players has left a wide open lane for tech platforms to capture consumer mindshare.
Official Statements and Industry Perspectives
The rapid commoditization of travel rewards by non-traditional entities has sparked intense debate among industry executives, fintech leaders, and hospitality analysts.
The FinTech Perspective: Unlocking Seamless Utility
Proponents of the embedded travel model argue that consumers are exhausted by fragmented loyalty schemes. Financial tech leaders emphasize that modern consumers prefer unified financial dashboards where travel rewards compound directly into everyday wealth-building or lifestyle utility.
"Our goal has always been to build a financial ecosystem that works harder for our customers," noted a product strategist familiar with the Robinhood-Duffel integration. "Travel is one of the largest discretionary expenses a household undertakes. By removing friction through modern infrastructure APIs and rewarding our cardholders with meaningful, tangible value—like 10 percent back on hotels—we are transforming a traditional expense into a wealth-retention mechanism."
The Hospitality and OTA Counter-Perspective: Diluting Brand Equity
Conversely, legacy travel executives have privately—and occasionally publicly—expressed concern over the commoditization of hotel inventory. When a hotel room is sold primarily on the basis of a 10 percent cash-back rebate provided by a third-party stock-trading app, the hotel property itself loses direct relationship control over the guest.
“Hotels spend millions cultivating guest satisfaction, loyalty, and brand equity,” notes a senior hospitality consultant based in New York. “When a consumer books a stay driven purely by a financial app’s cash-back incentive, the hotel becomes a commodity. The guest is loyal to the credit card or the rideshare app, not the property. This shifts pricing and distribution power away from hoteliers and into the hands of platform gatekeepers.”
Future Outlook: Where Is the 10 Percent War Heading?
As the dust settles on the initial wave of cross-industry disruption, the trajectory of travel rewards points toward several distinct structural developments over the next three to five years.
1. The Consolidation of Travel Infrastructure APIs
The barrier to entry for launching a branded travel service has effectively dropped to zero. As more infrastructure providers like Duffel enter the market, we can expect nearly every major consumer app—from fitness trackers to food delivery networks—to experiment with embedded travel booking modules. However, maintaining a sustained 10 percent margin subsidization will prove difficult for smaller players once venture capital funding tightens further.
2. Regulatory Scrutiny and Interchange Fee Pressures
Fintech-driven rewards models rely heavily on credit card interchange fees. As regulatory bodies globally scrutinize swipe fees and push for fee caps similar to those seen in other international markets, the underlying revenue engine supporting these high-yield travel rebates could face severe compression. If interchange revenues shrink, platforms may be forced to dial back their 10 percent cash-back offers or introduce stricter spending thresholds.
3. The Counter-Offensive by Hospitality Brands
Hotels are unlikely to sit idly by while tech giants siphon away their direct booking relationships. Expect major hospitality groups to double down on "Book Direct" exclusive perks—such as complimentary high-speed Wi-Fi, room upgrades, and experiential add-ons—that third-party fintech apps simply cannot replicate through cash-back alone. Furthermore, hotel loyalty programs may increasingly partner directly with alternative financial institutions to offer co-branded cards that rival the earnings power of standalone fintech disruptors.
Conclusion
The era of the proprietary travel loyalty program is giving way to the age of universal financial utility. When an investor buying shares on an app or a commuter hailing a ride can secure a better hotel rebate than a dedicated loyalty member booking directly on an OTA, the rules of engagement have permanently changed. The 10 percent hotel back offer is no longer just a promotional discount; it is the new baseline tax that non-travel tech giants must pay to capture the modern consumer’s wandering eye.