
October 5, 2026
Executive Overview
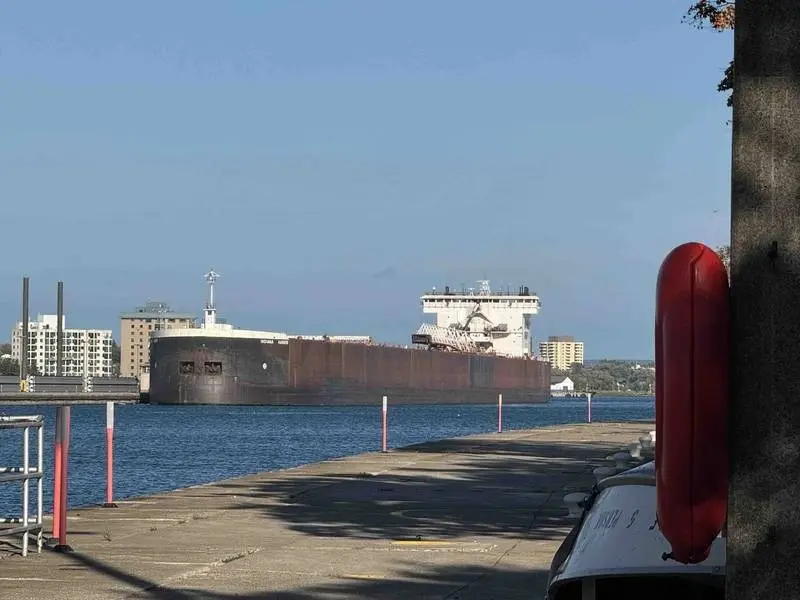
The domestic maritime supply chain faces a complex and uneven landscape as autumn begins. According to newly released data from the Lake Carriers’ Association (LCA), shipments of iron ore from U.S. ports on the Great Lakes experienced a modest contraction in September 2026, falling 1.2% year-over-year to 4.63 million net tons. While this single-month decline appears minor on the surface, a broader historical perspective reveals a more significant trend: September’s shipments lagged the month’s five-year average by a substantial 11.4%, signaling persistent headwinds in the domestic steel manufacturing supply chain and shifting logistics strategies among major industrial players.
Despite the late-summer lull, the year-to-date (YTD) outlook offers a silver lining. Across the first three quarters of 2026, cumulative iron ore loadings reached 32.16 million net tons, representing a 2.4% increase compared to the same period in 2025. However, this recovery remains incomplete. When compared against the historical baseline, YTD iron ore loadings are still 6.1% below their five-year average of 34.26 million net tons.
Great Lakes Iron Ore Shipments - September 2026 at a Glance:
• Monthly Total: 4,630,056 net tons (Down 1.2% vs. Sept 2025)
• Monthly vs. 5-Year Average: Down 11.4%
• Year-to-Date Total: 32,159,755 net tons (Up 2.4% vs. YTD 2025)
• YTD vs. 5-Year Average: Down 6.1%
This divergence—characterized by short-term monthly declines alongside modest year-to-date gains—underscores a structural transition within the Great Lakes shipping ecosystem. Regional performance has fractured. Traditional heavyweights like Duluth, Minnesota, are experiencing prolonged volume contractions, while ports like Marquette, Michigan, and Cleveland, Ohio, are seeing surges in traffic. These shifts reflect evolving corporate strategies among major steelmakers, changes in furnace operations, and the ongoing modernization of the Great Lakes bulk carrier fleet.
Detailed Chronology: The Great Lakes Shipping Arc (2021–2026)
To understand the state of the Great Lakes iron ore trade in September 2026, one must examine the macroeconomic cycles of the last five years.
September Iron Ore Shipments (2021–2026) in Net Tons:
2021:  5,361,020
2022:  5,059,487
2023:  5,572,059
2024:  5,464,298
2025:  4,686,719
2026:  4,630,056
The Post-Pandemic Highs (2021–2023)
In 2021, the Great Lakes maritime industry operated at near-maximum capacity, driven by a surge in post-pandemic demand for consumer goods, automotive manufacturing, and structural steel. September 2021 saw 5.36 million tons of iron ore move through U.S. ports, culminating in a robust YTD total of 37.39 million tons.
While 2022 experienced a sharp correction due to labor constraints, inflation, and temporary mill outages—dropping the YTD total to a low of 29.25 million tons—the industry rebounded vigorously in 2023. Backed by stable water levels and high demand from domestic automakers, September 2023 set a five-year monthly peak of 5.57 million tons, pushing YTD volumes back to 36.74 million tons.
The Shift Toward Rationalization (2024–2025)
By late 2024, the market began to cool. September 2024 shipments remained relatively stable at 5.46 million tons, but the underlying industrial demand was beginning to soften. High interest rates slowed commercial construction, and global steel price volatility prompted domestic producers to manage inventory more aggressively.
This culminated in a sharp downturn in 2025. September 2025 shipments plunged to 4.69 million tons—a drop of more than 14% compared to the previous year. The decline was driven by scheduled maintenance shutdowns at key blast furnaces, lower steel demand, and operational shifts as steelmakers transitioned toward electric arc furnace (EAF) technologies, which rely more on scrap metal than raw iron ore.
Stabilization and Divergence in 2026
September 2026 represents a period of stabilization, albeit at a lower baseline. The total of 4.63 million tons shows that the rapid declines of 2025 have leveled off. However, the failure to return to the 5-million-ton threshold indicates that the Great Lakes iron ore trade is adjusting to a "new normal." Corporate consolidation and vertical integration—such as Cleveland-Cliffs’ optimizing its mining assets in the Mesabi Range and its blast furnace operations in Ohio and Indiana—have permanently altered historical shipping corridors.
Supporting Context & Metrics: Port-by-Port Analysis
The overall decline of 1.2% in September 2026 masks significant volatility at individual loading facilities. The performance of the primary iron ore ports reveals a stark divide between lagging traditional harbors and booming specialized ports.
The Western Lake Superior Giants: Duluth and Superior
The Twin Ports of Duluth, Minnesota, and Superior, Wisconsin, present two very different operational stories.

- Duluth, MN: Once the undisputed powerhouse of Great Lakes iron ore, Duluth has suffered a steep decline. In September 2026, the port loaded just 467,060 net tons—a 22.8% drop from September 2025 (605,012 tons) and a staggering 47.5% drop from its five-year average of 889,188 tons. Looking at YTD figures, Duluth’s total of 5.00 million tons is nearly a million tons below its historical average, indicating a structural reduction in taconite throughput at its docks.
- Superior, WI: Conversely, Superior showed signs of resilience in September 2026, loading 952,030 net tons—an increase of 6.6% compared to September 2025. However, like Duluth, its broader performance is lagging. Superior’s YTD volume of 5.96 million tons remains more than 2 million tons below its five-year average of 8.04 million tons.
The North Shore and Upper Peninsula: Two Harbors, Silver Bay, and Marquette
- Two Harbors, MN: Located on Lake Superior’s north shore, Two Harbors remains the highest-volume iron ore port on the Great Lakes. In September 2026, it held steady at 1.48 million tons, virtually identical to its September 2025 performance. Its YTD total of 9.45 million tons makes up nearly 30% of the entire region’s iron ore shipping volume, proving its critical role as the primary conduit for northern Minnesota’s taconite mines.
- Silver Bay, MN: Silver Bay saw its September loadings drop to 425,581 tons, down 23.6% from September 2025. Because Silver Bay’s operations are closely tied to Cleveland-Cliffs’ Northshore Mining facility, its volume is highly sensitive to corporate decisions regarding pellet production types (such as the transition to low-silica DR-grade pellets used in direct-reduction steelmaking).
- Marquette, MI (Presque Isle): Marquette was the standout performer of September 2026. The port loaded 929,059 tons, representing a 13.8% increase over September 2025 and a massive 33.3% increase over its five-year average of 697,023 tons. Marquette’s YTD performance is equally impressive, reaching 5.97 million tons—well above its 4.69-million-ton average. This surge highlights the strategic importance of Michigan’s Tilden Mine and the efficiency of the Presque Isle dock in supplying regional steel mills.
Lower Lakes Transshipments: Cleveland and Ashtabula
- Cleveland, OH: Serving as both a receiving and transshipment hub, Cleveland Harbor handled 372,617 tons in September 2026, up 12.4% year-over-year. Its YTD volume of 3.16 million tons is more than 30% above its historical average, reflecting intense activity at Cleveland-Cliffs’ Cleveland Works and localized logistics optimization.
- Ashtabula, OH: After handling zero iron ore shipments for several consecutive years, Ashtabula recorded 34,181 tons YTD in 2026, marking a modest return to the active ledger.
Official Statements and Industry Perspectives
While the Lake Carriers’ Association maintains a strict policy of neutrality, issuing its data with the caveat that it "assumes no legal responsibility for the outcome of decisions made on the basis of this information," industry leaders and maritime analysts have voiced clear perspectives on the current shipping climate.
Infrastructure Bottlenecks and the Soo Locks
A recurring theme among Great Lakes vessel operators is the critical state of maritime infrastructure. Nearly all iron ore shipped from Lake Superior ports must transit the Soo Locks at Sault Ste. Marie, Michigan.
"The efficiency of the iron ore trade is entirely dependent on the reliability of the Poe Lock," says a veteran Great Lakes captain. "As we transition into the late autumn shipping season, when weather conditions deteriorate and demand peaks ahead of the winter closure, any unscheduled downtime at the locks would be catastrophic for the domestic steel industry."
The ongoing construction of a second Poe-sized lock remains a top priority for the LCA and regional stakeholders. Advocates argue that the project is vital for national security, ensuring that the massive 1,000-foot U.S.-flag bulk carriers—which carry the majority of the region’s taconite—have a redundant path of transit.
Fleet Modernization and Environmental Regulations
The shipping industry is also navigating strict environmental mandates, including ballast water management regulations and pressure to reduce carbon emissions. The U.S. Great Lakes fleet, protected by the Jones Act, has seen significant investment in recent years. Shipowners are repowering older vessels with more efficient engines and exploring alternative fuels to meet long-term sustainability goals. However, these capital investments require a predictable, high-volume shipping market to justify their costs—a dynamic made more difficult by the current volatility in monthly ore shipments.
Future Outlook: Q4 Pressures and Winter Closures
As the Great Lakes shipping industry enters the final quarter of 2026, operators are preparing for the most challenging and critical phase of the navigation season. The period between October and the closing of the Soo Locks in mid-January typically sees a surge in activity as steel mills stockpile raw materials to carry them through the winter freeze.
Key Factors Shaping the Q4 Great Lakes Shipping Outlook:
1. Stockpiling Demand: Steel mills accelerating raw material reserves before the winter freeze.
2. Soo Locks Closure: The hard deadline of January 15, 2027, for all Lake Superior transit.
3. Icebreaking Capabilities: Relying on U.S. and Canadian Coast Guard assets to keep channels clear.
4. Macroeconomic Drivers: Automotive production schedules and infrastructure spending.
The Rush to Stockpile
Integrated blast furnaces in Indiana, Ohio, and Pennsylvania rely on a steady flow of iron ore to maintain continuous operations. Because Lake Superior freezes over during the deep winter, preventing safe transit through key channels, shipping lines must maximize their tonnage over the next 90 days. If the modest downward trend seen in September persists into November and December, steelmakers may face tighter inventories in early spring 2027.
Weather and Icebreaking Preparedness
The success of the late-season push hinges on the severity of early winter weather and the availability of icebreaking assets. The Lake Carriers’ Association has historically advocated for stronger congressional funding for Coast Guard icebreakers, noting that inadequate icebreaking in key choke points like the St. Marys River, the Straits of Mackinac, and the St. Clair River can cause costly delays.
"Every day a vessel is stuck in the ice is a day that steel mills are drawing down their reserves," notes a maritime logistics analyst. "With the current fleet of icebreakers operating near their service limits, a sudden, early freeze in December 2026 could quickly erase the year-to-date gains we’ve seen so far."
Long-Term Industrial Forecast
Looking ahead to 2027, the Great Lakes iron ore trade will continue to serve as a bellwether for the broader U.S. manufacturing sector. While the transition toward scrap-based Electric Arc Furnaces presents a long-term challenge to raw ore volumes, high-quality steel applications—particularly in the automotive and defense sectors—still rely on the high-purity iron produced by traditional blast furnaces.
As long as this demand remains, the shipping lanes of the Great Lakes will remain a vital artery of American industry. However, the port-by-port divergence seen in September 2026 suggests that while the overall trade will endure, the routes, vessels, and harbors carrying this vital cargo are undergoing a permanent transformation.