
WASHINGTON — For the better part of three years, the hospitality sector’s relationship with artificial intelligence has been defined by an uncritical gold rush. Major hotel brands, regional operators, and independent boutiques alike rushed to adopt generative pre-trained transformers, automated guest-messaging bots, predictive pricing engines, and administrative automation suites. The technological imperative was simple: deploy or fall behind.
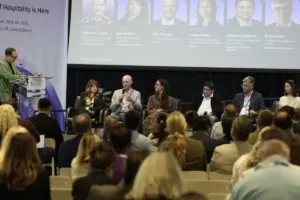
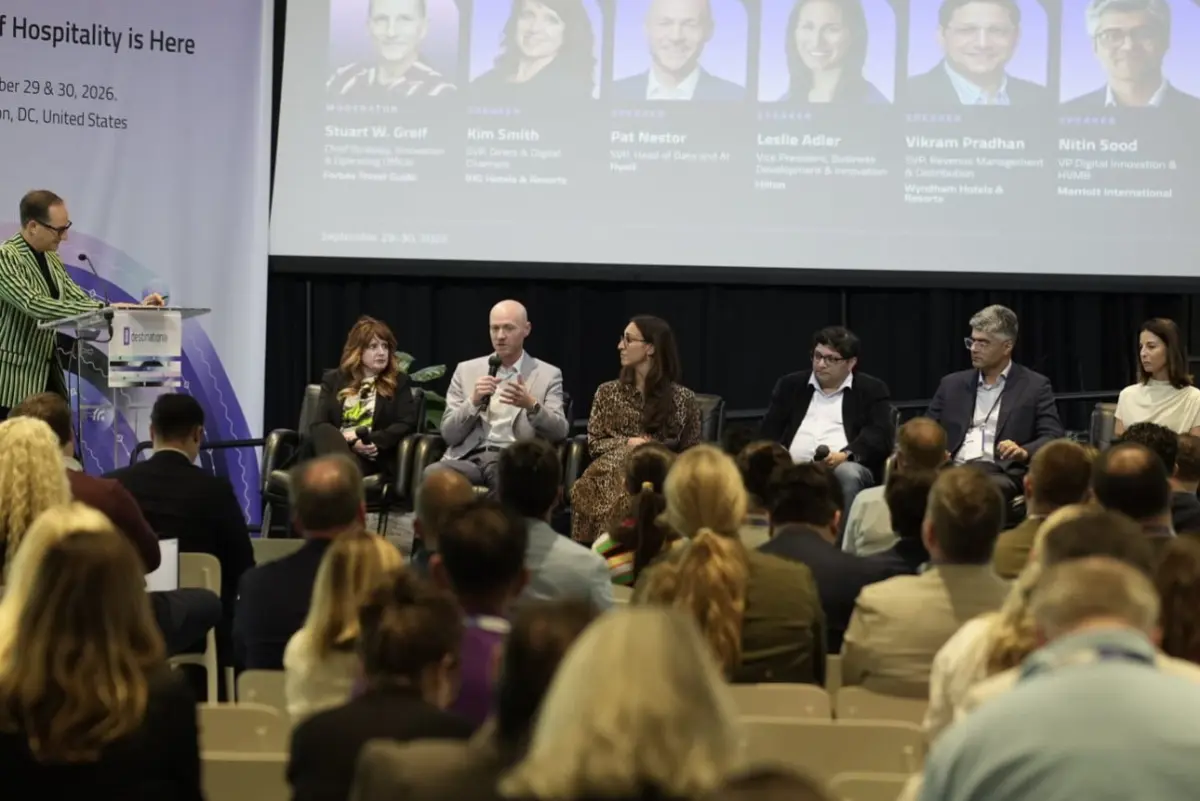
Yet, as hospitality executives converged on the nation’s capital this week for the high-profile Destination AI conference, the celebratory rhetoric surrounding rapid deployment gave way to a sober, hard-edged financial interrogation. Behind closed doors and on main-stage panels, a defining tension of the mid-2020s tech cycle came into sharp focus: Hotel companies know precisely what artificial intelligence is costing them. They are significantly less sure of what it is earning them.
This valuation gap—the chasm between massive capital expenditures, recurring software-as-a-service (SaaS) subscription fees, staggering compute and cloud infrastructure costs on one side, and tangible bottom-line revenue growth on the other—was the undisputed recurring theme of the summit. As the industry transitions from the initial honeymoon phase of experimentation to a mature era of fiscal accountability, hospitality leaders are confronting a reckoning that will dictate IT budgets, operational strategies, and vendor relationships for the remainder of the decade.
Executive Overview
The hospitality industry stands at a critical macroeconomic crossroads. For decades, hotel groups have operated on razor-thin operating margins, making capital allocation decisions subject to intense scrutiny from asset owners, franchisees, and Wall Street investors. The rapid integration of artificial intelligence represented a radical departure from traditional capital deployment, requiring heavy upfront investments in proprietary models, third-party integrations, and workforce retraining.
However, the metrics used to justify these expenditures have historically been soft. In the nascent stages of the AI boom, operational efficiency was king. Success was measured in hours saved, emails drafted, concierge requests processed, and localized customer service tickets resolved with minimal human touch.
While these micro-efficiencies undoubtedly streamlined daily workflows, finance departments and profit-and-loss (P&L) statement analysts are now asking a more existential question: Where do saved hours materialize on a balance sheet?
As executive leadership teams prepare their fiscal forecasts for the coming year, the tolerance for speculative, "black box" technology investments is evaporating. The mandate for 2026 and beyond is clear: AI must move from being an experimental line item in innovation budgets to a demonstrable profit driver that protects margins, enhances RevPAR (Revenue Per Available Room), and directly influences guest lifetime value.
Detailed Chronology: From Experimental Novelty to Financial Scrutiny
To understand how the hotel industry arrived at this inflection point of financial skepticism, it is necessary to trace the trajectory of AI adoption across the sector over the past several years.
Phase 1: The Pandemic-Era Pivot and Operational Necessity (2020–2022)
The foundational groundwork for modern hospitality AI was laid during the COVID-19 pandemic. Facing historic labor shortages, plummeting occupancy rates, and stringent public health protocols, hotels turned to automation out of sheer survival. Contactless check-ins, automated text-based guest communications, and rudimentary chatbots became standard operating procedures. During this phase, cost was secondary to operational continuity; technology was deployed to manage skeleton crews and reassure anxious travelers.
Phase 2: The Generative AI Gold Rush (2023–2024)
Following the public launch of breakthrough generative AI models, the hospitality sector experienced an unprecedented wave of FOMO (Fear of Missing Out). Major hotel groups rushed to announce partnerships with tech giants and specialized AI startups. Millions of dollars were funneled into pilot programs designed to revolutionize everything from dynamic room pricing and automated marketing copy generation to predictive housekeeping scheduling and voice-activated in-room assistants.
The industry narrative during this period was unabashedly optimistic. Conferences were dominated by panels discussing the theoretical limits of machine learning, neural networks, and prompt engineering. Little attention was paid to the long-term total cost of ownership (TCO) or granular ROI attribution.
Phase 3: The Integration Plateau and Vendor Proliferation (2025)
By 2025, the sheer volume of disparate AI tools began to create friction within hotel operations. Front-desk staff, revenue managers, and corporate marketers found themselves inundated with overlapping software platforms. A typical hotel group might be utilizing one AI tool for reputation management, another for dynamic pricing, a third for email marketing, and a fourth for internal knowledge management.
Crucially, these systems frequently operated in silos, failing to communicate effectively with legacy Property Management Systems (PMS) like Oracle OPERA or cloud-based customer relationship management (CRM) platforms. As subscription renewals arrived, corporate IT directors began tallying the cumulative financial drain of maintaining these fragmented tech stacks.
Phase 4: The Accountability Reckoning (Late 2026 and Beyond)
The current climate, crystallized at the Destination AI event, marks the definitive arrival of Phase 4. Chief Information Officers, Chief Financial Officers, and senior data executives are no longer evaluating AI based on its potential. They are auditing its performance. The era of writing blank checks for "innovation" has officially closed, replaced by rigorous financial audits and demand for empirical proof of value creation.
Supporting Context & Metrics: The Anatomy of the AI Cost-Value Gap
The friction between AI expenditure and P&L impact is not merely a philosophical debate; it is rooted in the complex economic realities of hotel operations.
The Cost Side of the Ledger
Calculating the true cost of enterprise AI in hospitality goes far beyond software licensing fees. Industry analysts point to several major cost drivers:
- Infrastructure and Compute Costs: Running or querying large language models at scale requires substantial cloud computing resources, the costs of which scale dynamically with guest interaction volume.
- Data Cleansing and Governance: AI is only as good as the data feeding it. Hotels have historically siloed customer data across disparate booking engines, loyalty programs, and on-property point-of-sale systems. Unifying this data to power effective AI models has required massive investments in data engineering and master data management.
- Integration and Maintenance: Custom API development to bridge modern AI tools with legacy, on-premise hotel infrastructure demands continuous developer hours and specialized technical talent.
- Change Management and Training: Retraining thousands of front-line hospitality workers—from housekeepers to general managers—represents a significant investment in time and lost productivity.
The Value Side of the Ledger
Conversely, quantifying the return on these investments has proved notoriously difficult. While a chatbot may handle 5,000 reservation inquiries a month, translating that operational metric into incremental net revenue requires complex attribution modeling.
- Did the chatbot capture bookings that would have otherwise been lost, or did it merely field inquiries from customers who would have eventually booked through the brand website anyway?
- Did labor-saving automation actually allow properties to reduce headcount, or did it simply reallocate staff to other tasks without reducing overall labor costs?
These are the precise questions that financial controllers are asking as they review preliminary budgets for the upcoming fiscal year.
Official Statements and Industry Insights
The mood at the Washington conference was characterized by a pragmatic realism. Industry leaders did not dismiss the power of artificial intelligence; rather, they acknowledged that the honeymoon phase has ended and the hard work of business integration has begun.
Weighing in on this shift, Pat Nestor, Senior Vice President of Data and AI at Hyatt, delivered one of the most quotable and widely discussed assessments of the event:
"We all know what the costs are right now. Certainly in the early days, everything was sort of measured in hours saved. OK, great. That’s helpful in terms of your own personal efficiency. But where does that live on a P&L sheet?"
Nestor’s critique went straight to the heart of corporate budgeting. Hours saved through automated spreadsheet generation or streamlined email drafting are valuable for employee morale, but they do not automatically translate into improved EBITDA (Earnings Before Interest, Taxes, Depreciation, and Amortization) unless those hours are parlayed into structural labor reductions or revenue-generating activities.
Predicting an aggressive tightening of corporate purse strings, Nestor noted that the upcoming fiscal cycles will see unprecedented scrutiny:
"We’ve deployed these things. Where is the value of it?"
Detailing Hyatt’s internal strategic pivot, Nestor explained that the hospitality giant has consciously moved its internal focus from mere "adoption" to rigorous "absorption." The fundamental question guiding executive decision-making is no longer whether a property or department is using AI, but whether the organization is successfully "extracting the value" from the infrastructure it has already built and paid for.
Other hospitality executives echoed Nestor’s sentiments during panel discussions, emphasizing that vendors selling AI solutions can no longer rely on buzzwords like "machine learning" or "neural networks" to close enterprise contracts. Vendors must now provide clear, verifiable case studies demonstrating direct impacts on conversion rates, direct booking acquisition costs, and average daily rate (ADR) optimization.
Future Outlook: The Road Ahead for Hospitality AI
As the hotel industry navigates this period of financial introspection, the trajectory of artificial intelligence is expected to mature significantly. Several key trends will define the next phase of AI integration in hospitality:
1. Shift Toward Proprietary and Domain-Specific Models
Generic, off-the-shelf generative AI tools are losing favor among major hotel groups. In their place, brands are investing in fine-tuned, domain-specific models trained on proprietary guest data, loyalty history, and brand standards. These bespoke models are designed to deliver hyper-personalized guest experiences that directly drive loyalty and repeat bookings—metrics that live clearly and unmistakably on the P&L sheet.
2. Rigorous Attribution Modeling
Enterprise software developers and internal IT teams are racing to build sophisticated attribution dashboards. These tools aim to connect AI touchpoints directly to financial outcomes, tracking a guest from an AI-powered personalized web recommendation all the way through to on-property ancillary spending at the spa or signature restaurant. Without this level of tracking, future AI budgets face severe contraction.
3. Consolidation of the Tech Stack
The proliferation of point-solution AI vendors is unsustainable. Hotel operators are actively seeking out unified technology partners who can provide end-to-end AI capabilities—covering everything from revenue management and marketing to operations and guest communications—within a single, cohesive ecosystem. This consolidation will reduce integration costs and eliminate software redundancies.
4. Human-Centric Hospitality
Ultimately, industry leaders at the Destination AI event agreed that technology in hospitality can never fully replace the human element that defines true luxury and service. The most successful AI applications moving forward will be those that operate invisibly in the background—optimizing supply chains, predicting maintenance issues before they disrupt guests, and empowering front-line staff with real-time data to deliver deeply personalized human interactions.
Conclusion
The artificial intelligence revolution in the hotel industry has entered its adulthood. The era of enthusiastic experimentation, fueled by novelty and fear of obsolescence, has been superseded by an era of disciplined financial governance.
As Hyatt’s Pat Nestor and his industry peers made abundantly clear in Washington, the technology has proven its ability to save time and streamline workflows. Now, the definitive test of artificial intelligence in hospitality is much starker: it must prove its worth on the balance sheet. For hotel groups navigating the competitive landscape of the late 2020s, the message is unequivocal—innovate with purpose, or justify the cost.