


Executive Overview
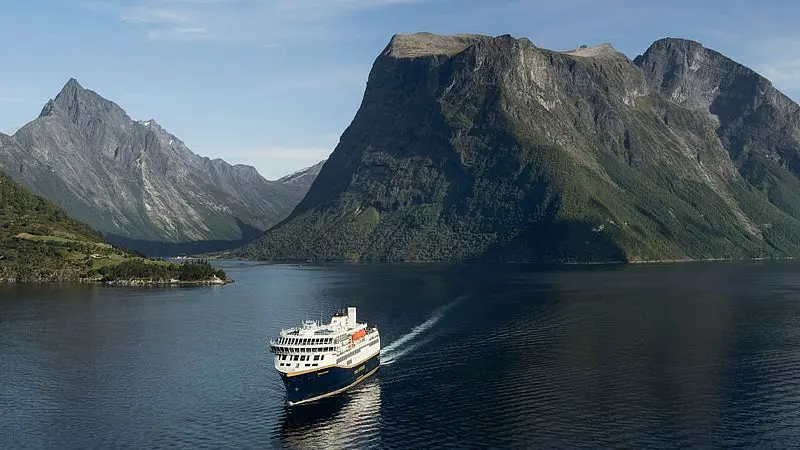
Norwegian coastal cruise operator Havila Voyages (Havila Kystruten) has released its financial and operational results for the second quarter of 2026, showcasing a period of robust financial growth, heightened operational efficiency, and significant progress in fleet decarbonization. The operator achieved an operating revenue of NOK 479 million during the three-month period ending June 30, 2026—marking a 15% year-on-year increase compared to the corresponding period in 2025.
Driven by rising occupancy rates, elevated onboard passenger expenditure, and strict capacity management along the historic coastal express route between Bergen and Kirkenes, the company’s earnings before interest, taxes, depreciation, and amortization (EBITDA) rose by 24% year-on-year to NOK 98 million. This profit growth lifted Havila Voyages’ EBITDA margin from 19% in Q2 2025 to 21% in Q2 2026, underscoring the financial leverage inherent in full fleet utilization and optimized yield strategies.
+-----------------------------------------------------------------------+
|                      HAVILA VOYAGES Q2 2026 AT A GLANCE               |
+--------------------------+-------------------+------------------------+
| Metric                   | Q2 2026 Value     | YoY Change / Margin    |
+--------------------------+-------------------+------------------------+
| Operating Revenue        | NOK 479 million   | +15%                   |
| EBITDA                   | NOK 98 million    | +24%                   |
| EBITDA Margin            | 21%               | +200 bps (vs 19%)      |
| Average Fleet Occupancy  | 83%               | +9 percentage points   |
| Passenger Nights         | 99,800            | +17%                   |
| Ticket Revenue           | --                | +10%                   |
| Onboard Revenue          | --                | +32%                   |
| Operational Uptime       | 100%              | 4-ship full deployment |
| CO2 Reductions           | -36%              | Vs. 2017 baseline      |
+--------------------------+-------------------+------------------------+
Operationally, the cruise line recorded an average fleet-wide occupancy rate of 83%, up nine percentage points from the 74% logged in Q2 2025. Total passenger nights surged by 17% to 99,800, driven by steady demand from international travelers seeking low-impact, premium travel through Norway’s fjords. Crucially, the operational performance was bolstered by a 100% uptime rating across all four of the company’s flagship vessels: Havila Capella, Havila Castor, Havila Polaris, and Havila Pollux.
Alongside its core financial metrics, the operator confirmed a 36% reduction in carbon dioxide ($textCO_2$) emissions compared to the Norwegian Ministry of Transport’s 2017 reference baseline for the coastal route. This reduction highlights the commercial viability of large-scale hybrid-electric maritime propulsion in sensitive arctic ecosystems.
Detailed Chronology
The Transition to Full Fleet Deployment (2021–2026)
To understand the financial dynamics of Havila Voyages’ Q2 2026 performance, the company’s progress must be viewed through the lens of its multi-year fleet transition and structural ramp-up along the Norwegian coastal route (Kystruten).
- 2018–2021: Tender Award and Technological Design: Following the Norwegian government’s decision to divide the historic coastal contract between incumbent operator Hurtigruten and new entrant Havila Kystruten, Havila secured a ten-year government contract to operate four purpose-built passenger and cargo vessels. The mandate required significant cuts in local and global greenhouse gas emissions, prompting Havila to construct vessels featuring 8.6 megawatt-hour (MWh) battery packs—the largest battery installations deployed on commercial passenger ships at the time.
- 2021–2023: Fleet Deliveries and External Headwinds: Havila Voyages entered active service with its first ship, Havila Capella, in late 2021. However, initial operations were disrupted by supply chain bottlenecks, shipyard delays, and geopolitical developments that forced a legal and financial restructuring of the fleet’s leasing arrangements. Despite these challenges, Havila Castor entered service in 2022, followed by Havila Polaris and Havila Pollux in mid-to-late 2023.
- 2024–2025: Operational Stabilization and Yield Optimization: By early 2024, all four vessels were fully operational, delivering a reliable 11-day round-trip service across 34 ports of call along the western and northern coasts of Norway. The company shifted its strategic focus from operational deployment to commercial yield management, brand awareness in key overseas markets (including North America, the United Kingdom, and DACH countries), and shore-side grid integration.
- Q2 2026: Financial Maturation: The second quarter of 2026 marks the culmination of this multi-year rollout. With all four vessels operating at maximum technical reliability, Havila achieved uninterrupted service throughout the spring and early summer travel season, converting high demand during the fjord-cruising months into record quarterly revenues and expanded margins.
CHRONOLOGY: HAVILA VOYAGES FLEET EVOLUTION
========================================================================================
2018         2021              2022              2023              2024-2025      Q2 2026
 |------------|-----------------|-----------------|-----------------|--------------|
 Coastal      Havila Capella    Havila Castor     Polaris & Pollux  Optimization   100% Uptime
 Tender       Enters Service    Enters Service    Delivered         Phase          NOK 479M Rev
 Awarded      (First Hybrid)                      (4-Ship Fleet)    Yield Focus    NOK 98M EBITDA
Supporting Context & Metrics Analysis
Havila Voyages’ second-quarter financial performance reflects both top-line top-tier expansion and underlying cost efficiency, driven by a deliberate shift toward higher-margin revenue channels.
Q2 2025 vs. Q2 2026 REVENUE & OCCUPANCY EVOLUTION
=================================================
Revenue (NOK M)   : [Q2 2025: 416M] --------> [Q2 2026: 479M] (+15%)
EBITDA (NOK M)    : [Q2 2025:  79M] ----> [Q2 2026:  98M]     (+24%)
Occupancy Rate    : [Q2 2025:  74%] --> [Q2 2026:  83%]       (+9% pts)
Passenger Nights  : [Q2 2025: 85.3K] ---> [Q2 2026: 99.8K]   (+17%)
Top-Line Revenue Structure: Ticket vs. Onboard Growth
Total operating revenue increased by 15% to NOK 479 million, supported by a dual-revenue strategy that decouples core passenger transportation from discretionary leisure spending onboard.
REVENUE DYNAMICS BREAKDOWN (YoY Growth)
--------------------------------------------------------------------
Ticket Revenue    : [████████████████████] +10%
Onboard Revenue   : [████████████████████████████████████████] +32%
Passenger Nights  : [████████████████████████████] +17%
--------------------------------------------------------------------- Ticket Revenue (+10% YoY): Base passage sales grew at a steady pace, supported by higher occupancy levels and targeted pricing adjustments. While full-route round-trip passengers (Bergen–Kirkenes–Bergen) formed the core foundation of ticket revenue, regional port-to-port passenger volume also held steady, meeting the public transport mandates set by the Norwegian Ministry of Transport.
- Onboard Revenue (+32% YoY): Outpacing ticket growth, onboard sales recorded a 32% increase. This surge highlights the success of Havila’s localized dining model and expanded shore excursion menu. By eschewing traditional cruise buffets in favor of à la carte dining sourced from regional Norwegian producers along the route, the company enhanced per-passenger spending. Additional high-margin offerings—such as guided local excursions, premium beverage packages, and retail sales—contributed significantly to the revenue total.
Capacity Management and Fleet Utilization
The increase in passenger nights to 99,800 (+17%) was achieved without adding physical capacity, as the fleet remained anchored at four operational ships. Instead, performance was driven by load factor optimization:
- Average Occupancy: Rising from 74% in Q2 2025 to 83% in Q2 2026, the 9-percentage-point gain demonstrates stronger booking conversion during shoulder-season weeks in April and May, which historically trailed peak summer months.
- Operational Uptime: Reaching 100% technical availability across all four vessels eliminated unexpected cancellations, refund costs, and alternative transportation liabilities. Maintaining high reliability is essential on the Norwegian coast, where harsh weather conditions and tight port turnarounds regularly test ship operations.
Margin Expansion and Cost Discipline
EBITDA grew by 24% to NOK 98 million, expanding the company’s EBITDA margin from 19% to 21%. This margin expansion underscores key operational efficiencies:
EBITDA MARGIN EXPANSION (Q2 2025 vs Q2 2026)
--------------------------------------------------------------------
Q2 2025: [███████████████████] 19%
Q2 2026: [█████████████████████] 21%  (+200 basis points)
--------------------------------------------------------------------- Fuel and Energy Cost Management: Havila’s hybrid-electric architecture allows its ships to run on LNG (Liquefied Natural Gas) combined with large battery packs. By charging batteries at ports using cheap hydro-electric power from the Norwegian domestic grid, the company reduced its reliance on fossil fuels, insulating operating costs from volatile marine gas oil (MGO) and LNG market prices.
- Fixed Cost Absorption: With the four-ship fleet fully built out, administrative overhead, port logistics, and marketing expenses were spread across a larger volume of passenger nights, leading to lower unit operating costs per available berth night (ABN).
Environmental Metrics and Decarbonization Impact
Havila Voyages reported that its fleet reduced $textCO_2$ emissions by 36% compared to the 2017 baseline established for the Norwegian coastal contract.
CO2 EMISSION REDUCTIONS RELATIVE TO 2017 BASELINE
========================================================================
2017 Coastal Baseline : [████████████████████████████████████████] 100%
Havila Q2 2026 Level  : [█████████████████████████] 64% (-36% Reduction)
========================================================================
This emission reduction is achieved through several combined technologies:
- Pure Electric Fjord Navigation: Ships operate solely on battery power for up to four hours at a time, eliminating direct emissions when sailing through vulnerable areas like the Geirangerfjord and the UNESCO-listed West Norwegian Fjords.
- Shore Power Integration: High-capacity shore connections allow the fleet to draw clean electricity while docked in major ports such as Bergen, Ålesund, Trondheim, and Bodø, turning off auxiliary engines during loading operations.
- Hull Optimization and Energy Recovery: Hydrodynamic hull designs and onboard heat recovery systems reduce overall energy consumption during open-sea transit across the Norwegian Sea and the Barents Sea.
Official Statements & Strategic Alignment
Executive commentary surrounding the Q2 2026 release highlights how financial growth and environmental responsibility can reinforce one another within modern maritime transport.
A key focus for Havila Voyages’ leadership team has been translating operational efficiency into consistent yield growth, ensuring that the company’s capital-intensive investments in green technology yield measurable economic returns.
Reflecting on the quarterly results, Havila Voyages’ executive team emphasized the strategic importance of complete fleet availability and growing consumer interest in eco-friendly travel:
"Achieving 100% operational uptime across our four coastal vessels during the second quarter demonstrates the maturity of our marine operations and the reliability of our hybrid-electric technology. Our financial growth—driven by a 32% increase in onboard revenue and an EBITDA margin expansion to 21%—proves that modern travelers are willing to support high-quality, sustainable travel experiences along the Norwegian coast.
Our ability to cut carbon emissions by 36% compared to historical baselines is not merely an environmental achievement; it is a core business strategy that lowers energy costs, ensures compliance with tightening European Union and Norwegian regulations, and positions Havila Voyages as an industry leader in high-latitude maritime decarbonization."
The performance aligns closely with broader regulatory and policy trends across Northern Europe. The Norwegian Parliament (Stortinget) has mandated zero-emission operations in its heritage fjords, a policy setting that favors operators with advanced battery-electric propulsion.
By achieving significant emissions cuts well ahead of regulatory deadlines, Havila Voyages has insulated its business model against prospective carbon taxes, marine fuel surcharges, and municipal port access penalties.
Future Outlook & Market Implications
Booking Trajectory and Q3 Expectations
Looking ahead to the second half of 2026, Havila Voyages reports sustained booking momentum. The third quarter, which encompasses the peak summer tourism months of July and August, traditionally generates the highest passenger yields along the Norwegian coast.
Preliminary booking indicators for Q3 2026 remain strong, driven by international long-haul markets—particularly North America and East Asia—where consumer demand for northern European destination travel remains robust.
FORWARD LOOKING INDICATORS & MID-TERM CATALYSTS
--------------------------------------------------------------------------
Current Horizon  : Q3 2026 Peak Season (Strong advance booking coverage)
Mid-Term Horizon : Winter Aurora Season (High demand for shoulder voyages)
Long-Term Focus  : IMO 2030 / EU ETS Carbon compliance readiness
--------------------------------------------------------------------------
Furthermore, advance bookings for the autumn and winter seasons—marketed around Northern Lights tours and winter activity excursions—are outpacing historic trends. This indicates that Havila’s strategy to smooth out seasonal demand volatility along the northern stretches of the route is gaining traction.
Strategic Priorities and Risk Landscape
While the immediate outlook is positive, management’s forward strategy addresses several operational and macroeconomic considerations:
- Yield Optimization vs. Capacity Limits: With the fleet capped at four vessels under the terms of the state coastal contract, long-term top-line growth relies on increasing average revenue per passenger night rather than expansion of total berth capacity. Consequently, management is focusing on yield management software, dynamic pricing models, and expanded shore-excursion partnerships to drive onboard spending.
- Macroeconomic and Currency Sensitivity: A significant portion of Havila’s customer base originates outside the eurozone and Norway. While a softer Norwegian Krone (NOK) makes travel to Norway more affordable for foreign visitors, it increases foreign currency-denominated debt servicing costs and international supplier expenses.
- Fuel and Grid Cost Dynamics: Although hybrid-electric technology reduces fossil fuel consumption, the operator remains exposed to regional fluctuations in electricity spot prices across Norway’s price zones (NO1 through NO5), alongside local LNG bunker fuel indices. Ongoing investments in energy storage optimization aim to mitigate these fluctuations.
Industry Implications
Havila Voyages’ performance offers a valuable case study for the wider cruise and commercial maritime industries. As global regulators—including the International Maritime Organization (IMO) and the European Commission through the EU Emissions Trading System (EU ETS)—tighten greenhouse gas targets for shipping, Havila’s success shows that high capital expenditure on low-emission propulsion can be recouped through lower energy use, strong customer demand, and premium pricing.
By combining low-emission maritime technology with local product sourcing and dependable transport service, Havila Voyages has established a financially viable model for sustainable coastal shipping. As the company moves into the second half of 2026, its focus remains on operational reliability, margin expansion, and supporting decarbonization efforts across the Arctic cruising market.