
Executive Overview
The global shipping industry stands at a critical decarbonization crossroads. With the International Maritime Organization (IMO) pushing for net-zero greenhouse gas emissions by or around 2050, shipowners, shipbuilders, and policymakers are scrambling to find viable alternative fuels. While ammonia, methanol, and hydrogen dominate industry headlines, none possess the energy density, operational range, and true zero-emission profile of nuclear power.
The release of the U.S. Center for Maritime Innovation Report: Small Modular Reactor (SMR) Technologies for Maritime Applications on May 19, 2026, was highly anticipated as a roadmap for this transition. However, the report has sparked intense debate within the maritime community. Rather than addressing the technical bottlenecks and the glacial pace of physical reactor integration, the report focuses heavily on two perceived barriers:
- Complex insurance and liability obstacles.
- Adverse public perception regarding commercial nuclear vessels.
To many seasoned maritime executives and insurance underwriters, this focus represents a fundamental misunderstanding of commercial shipping dynamics. Critics argue that these "paper obstacles" are marginal, hypothetical concerns that distract from the real issue: the lack of physical, operational prototype vessels. By analyzing historical precedents, the mechanics of maritime insurance, and shifting global attitudes toward nuclear energy, this investigative report examines whether the industry is worrying about "the edge of the world" while missing the boat on technological leadership.
Detailed Chronology
The dream of civilian nuclear-powered shipping is not new, but its modern revival via Small Modular Reactors (SMRs) represents a distinct historical chapter. Understanding how the industry arrived at the current policy bottleneck requires looking at both past failures and recent regulatory milestones.
[1959-1962] NS Savannah Launched (High operating costs, not public protests, lead to decommissioning)
       │
[1980s-Present] Naval Dominance (US, UK, French, Russian navies safely operate nuclear vessels)
       │
[Jan 2025] "NR-1" Retrospective (Renewed industry interest in compact maritime reactors)
       │
[May 19, 2026] U.S. Center for Maritime Innovation publishes SMR Report
       │
[June 2026] MARAD Administrator Carmel addresses Insurance Forum; Shipowners demand "steel in the water"
The Legacy of the Pioneers (1959–1970s)
The United States launched the NS Savannah in 1959 as part of President Eisenhower’s "Atoms for Peace" initiative. While technically successful, the vessel was retired in 1971. Crucially, its retirement was driven by high operating costs, lack of specialized shore infrastructure, and the uneconomical nature of its first-generation reactor—not by public protests or insurmountable insurance bans. Similar fates befell West Germany’s Otto Hahn and Japan’s Mutsu, establishing a long-standing industry assumption that civilian nuclear power was economically unviable.
The Naval Era of Safe Operation (1960s–Present)
While commercial nuclear shipping stalled, military applications flourished. For over six decades, the U.S. Navy, the British Royal Navy, the French Navy, and the Russian fleet (including its civilian nuclear-powered icebreaker fleet) have operated nuclear reactors at sea. Thousands of sailors have lived in close proximity to these reactors for months at a time without incident, establishing an unparalleled safety record that directly challenges the narrative of "inherent maritime risk."
The SMR Renaissance and Policy Gridlock (2025–2026)
By January 2025, maritime analysts began revisiting compact reactor designs, pointing to historical assets like the Navy’s deep-submergence vessel NR-1 as proof that small-scale, highly reliable reactors could operate safely under extreme conditions.
This momentum culminated in the May 19, 2026, report by the U.S. Center for Maritime Innovation. However, instead of providing a engineering blueprint, the report relied heavily on panel polls among conference participants, identifying public opposition and insurance liabilities as the primary hurdles. This focus was quickly mirrored in policy circles, leading to heated discussions at maritime forums throughout the summer of 2026.
Supporting Context & Metrics
To assess whether insurance and public perception are genuine roadblocks or merely administrative distractions, we must analyze the structural realities of the maritime underwriting market and modern public opinion data.
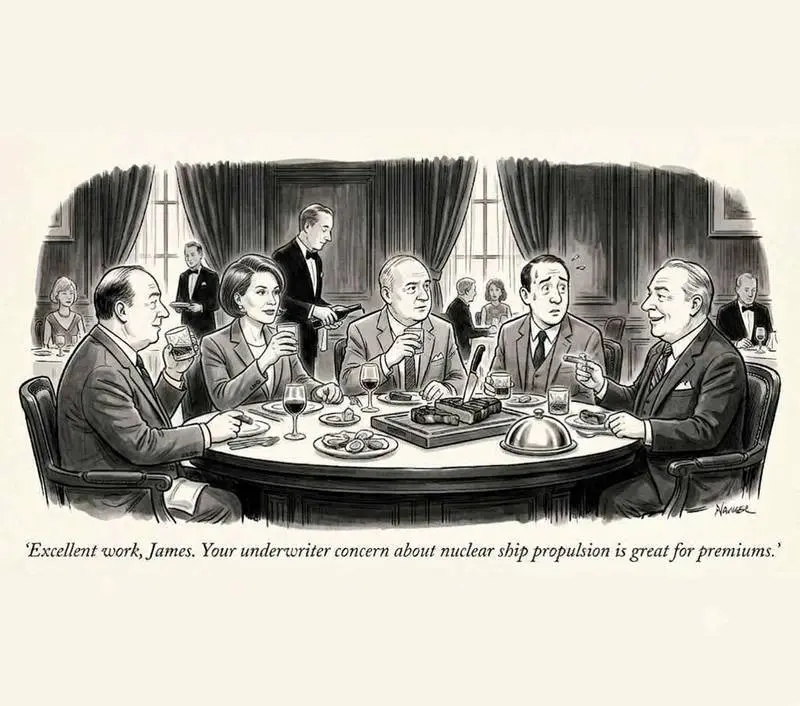
The Reality of Maritime Insurance: Premiums Paper Over Risk
The argument that SMR-powered vessels are "uninsurable" ignores the fundamental mechanics of the marine insurance industry. For centuries, underwriters have priced risk based on uncertainty; as long as a risk can be calculated, it can be insured.
In commercial shipping, liability is typically managed through a combination of:
- Protection and Indemnity (P&I) Clubs: Mutual insurance associations that provide cover for open-ended risks, including third-party liability and environmental damage.
- Hull and Machinery (H&M) Underwriters: Insurers covering physical damage to the ship and its propulsion systems.
- National and International Liability Frameworks: Historical precedents like the Oil Pollution Act of 1990 (OPA 90) demonstrate that when major environmental risks emerge, the market adapts by restructuring liability caps and raising premiums, rather than refusing coverage outright.
+-----------------------------------------------------------------------------+
|                          MARITIME RISK ASSESSMENT                           |
+-----------------------------------------------------------------------------+
|  "Uninsurable" Myth                                                         |
|  [ Risk of New Tech ] ──> [ Underwriter Analysis ] ──> [ Higher Premium ]   |
|                                                                │            |
|  Commercial Reality                                            ▼            |
|  [ Shipowner Pays Premium ] ──> [ Vessel Sails ] ──> [ Risk Papered Over ]  |
+-----------------------------------------------------------------------------+
As one senior marine underwriter with 50 years of experience noted:
"Underwriters always have concerns, but those concerns are always papered over with premiums. That is the nature of insurance. To worry about that as a potential issue is as useless as worrying about taxes. Like taxes, insurance will be a problem, and like taxes, it will be resolved."
Public Perception: The NIMBY Myth on the High Seas
A core finding of the May 2026 report was the threat of "negative public perception." However, empirical data suggests this concern is largely hypothetical. When polled on land-based nuclear power, global public support has reached historic highs.
| Region / Metric | Public Support for Nuclear Power (Post-2020) | Key Driver |
|---|---|---|
| United States | 60% – 70% | Climate change concerns & energy security |
| European Union | 55% – 65% | Decarbonization mandates & grid stability |
| Global Maritime | No empirical negative data | High-seas operations are invisible to the public |
Furthermore, the "Not In My Backyard" (NIMBY) phenomenon—the primary driver of opposition to terrestrial nuclear plants—does not apply to international shipping. The ocean has no "backyards." History shows that when the public does interact with modern nuclear vessels, the reaction is overwhelmingly positive or indifferent.
For example, the commissioning of the Virginia-class fast-attack submarine USS New Jersey drew thousands of enthusiastic civilian spectators, with local communities celebrating the vessel’s arrival. The public does not fear the technology; they are simply unfamiliar with its commercial application because no modern commercial vessels exist for them to evaluate.
Official Statements
The tension between regulatory caution and entrepreneurial drive was on full display during a major maritime insurance conference in June 2026.
The Regulatory Perspective
The Maritime Administration (MARAD) has taken a cautious, policy-first approach. During his keynote address, MARAD Administrator Carmel focused extensively on the regulatory, legal, and insurance frameworks required before an SMR-powered commercial vessel can enter U.S. ports.
"We must address the legal architecture of liability before we can allow these reactors into our commercial waterways," Carmel stated. "Without international consensus on liability limits and indemnification, shipowners will find themselves locked out of major global ports."
The Shipowner Perspective
This bureaucratic caution met immediate resistance from practical operators. Sitting in the audience, a prominent international shipowner dismissed the regulatory hand-wringing:
"Who cares about insurance? Tell me I can build ships with SMRs, and we will figure out the insurance on the fly. That is what shipowners do. We find a technology that works, we order the vessels, and we clear the path with our underwriters and suppliers. You cannot insure a ghost. Build the ship first."
This sentiment highlights a growing rift: regulators want a complete legal framework before a keel is laid, while the industry argues that the legal framework can only be forged in response to a physical vessel.
Future Outlook
If the maritime industry continues to focus on theoretical public pushback and administrative insurance hurdles, it risks falling into a state of permanent developmental paralysis.
The Cost of Delay
The failure of early nuclear ships like the NS Savannah was ultimately economic, driven by the massive capital expenditure of bespoke, first-generation reactors. Modern SMRs, designed for factory fabrication and modular installation, solve this economic puzzle. However, the window of opportunity is closing. While Western regulators debate policy, state-backed competitors in Russia and China are actively expanding their fleets of nuclear-powered icebreakers and floating nuclear power plants, gaining invaluable operational data.
                  THE PATH TO NUCLEAR DECARBONIZATION

   TRADITIONAL REGULATORY PATH           PRAGMATIC INDUSTRIAL PATH
  ┌──────────────────────────┐          ┌──────────────────────────┐
  │   Draft Policy & Laws    │          │  Build Prototype Vessel  │
  └────────────┬─────────────┘          └────────────┬─────────────┘
               ▼                                     ▼
  ┌──────────────────────────┐          ┌──────────────────────────┐
  │  Debate Insurance Risks  │          │ Test Operational Safety  │
  └────────────┬─────────────┘          └────────────┬─────────────┘
               ▼                                     ▼
  ┌──────────────────────────┐          ┌──────────────────────────┐
  │  Poll Uninformed Public  │          │  Underwriters Price Risk │
  └────────────┬─────────────┘          └────────────┬─────────────┘
               ▼                                     ▼
  ┌──────────────────────────┐          ┌──────────────────────────┐
  │   Permanent Paralysis    │          │ Commercial Fleet Rollout │
  └──────────────────────────┘          └──────────────────────────┘
Moving Mountains, One Shovel at a Time
To achieve true zero-emission shipping, the maritime industry must shift its focus from "edge of the world" concerns to practical engineering.
- Establish Experimental Corridors: Bilateral agreements between progressive maritime nations to allow prototype SMR cargo vessels to operate along specific, high-volume trade routes.
- Leverage Class Societies: Utilize organizations like the American Bureau of Shipping (ABS) and DNV to establish technical safety standards that run parallel to reactor development, bypassing slow-moving multilateral treaties.
- Build the "Shovel": Shift public funding from theoretical impact studies to public-private partnerships aimed at building a single, operational, SMR-powered commercial container ship.
As the industry looks toward the 2030s, the lesson of the May 2026 report is clear. You can only get a real public and financial reaction to a real thing. If the global shipping industry wants to solve its carbon crisis, it must stop polling the public about hypothetical dangers, stop treating insurance as an insurmountable wall, and start building the future of maritime propulsion.