
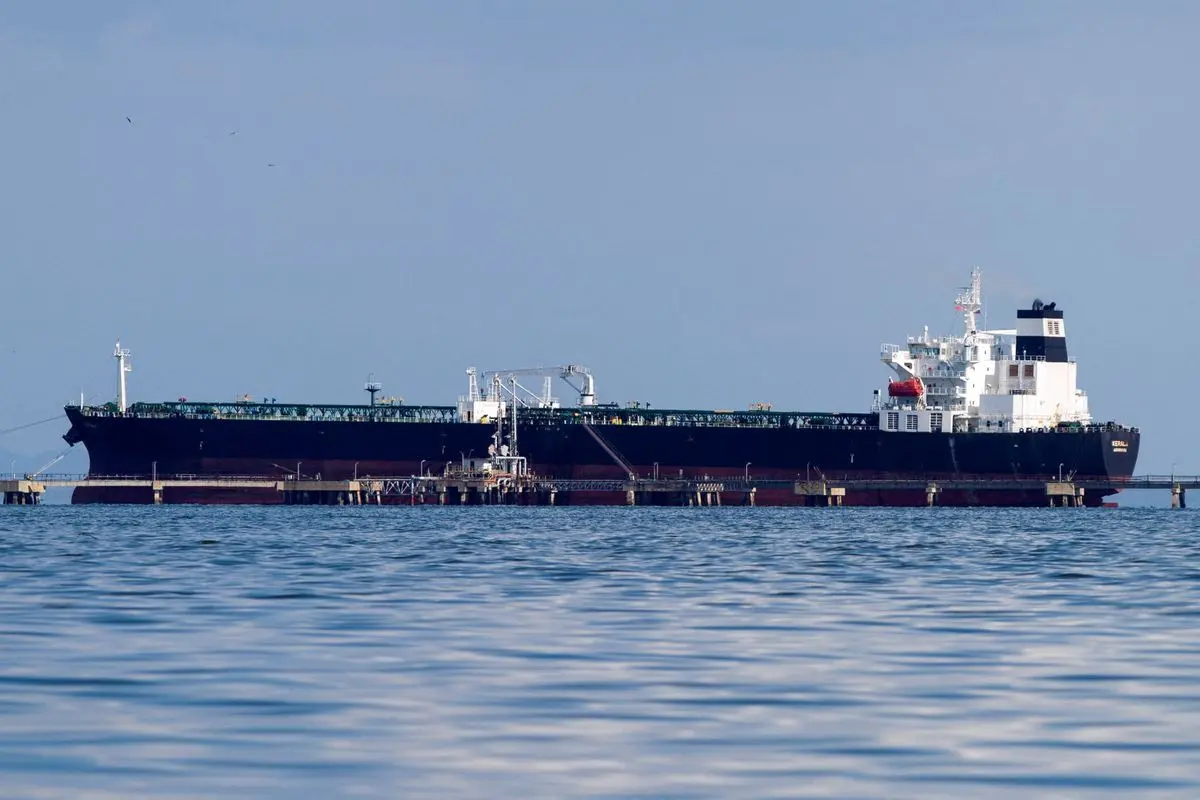
Executive Overview: The Geopolitical Squeeze on Venezuelan Crude
A high-stakes battle over profit margins is unfolding in the Caribbean. Global commodity trading giants Vitol and Trafigura are locked in intense negotiations with Venezuela’s state-owned oil enterprise, PDVSA, demanding steeper discounts on the country’s flagship heavy crude grade, Merey. This aggressive pushback from two of the world’s largest independent oil traders is driven by a dramatic surge in global maritime freight rates. The escalating transportation costs threaten to erase the trading houses’ margins, complicating Washington’s ambitious plans to rapidly revive the South American nation’s energy sector.
VENEZUELAN CRUDE DISCOUNT ESCALATION (2026)
(Discounts relative to Brent Benchmark)

[PDVSA Formula Price] -----------> ~$14.00/bbl discount (August Official)
[Joint Venture Partner Sales] ----> $12.00 - $13.00/bbl discount
[Intermediary Resale Price] -----> $16.00/bbl discount
[Vitol & Trafigura Bids] ---------> $18.00 - $20.00/bbl discount (Proposed)
The current standoff highlights the operational challenges of navigating Venezuela’s volatile energy market. Following major geopolitical shifts in early 2026—including the capture of former President Nicolás Maduro by U.S. forces in January and the subsequent outbreak of the U.S.-Iran war in February—Vitol and Trafigura emerged as the dominant players controlling Venezuelan crude flows. Together, they manage over half of the OPEC member’s exports, transporting approximately 597,000 barrels per day (bpd).
However, the maritime logistical networks that connect Venezuela’s primary loading terminals to refineries in the United States and Europe are under severe strain. With global tanker rates reaching historic highs due to widespread geopolitical conflict and shipping disruptions, the cost of transporting Venezuelan heavy crude has nearly tripled since the start of the year. This logistics bottleneck has shifted the balance of power, forcing intermediaries to demand deeper discounts to offset the rising cost of sea transport. Consequently, PDVSA is facing renewed financial pressure just as it attempts to bypass middlemen and maximize its cash flow.
Detailed Chronology: From Sanctions Relief to War-Time Logistics (2025–2026)
To understand the current impasse between international trading desks and PDVSA, one must trace the rapid sequence of political and military events that have reshaped the global energy landscape over the past year.
Timeline of Key Events Shaping Venezuela's Oil Sector
┌────────────────────────────────────────────────────────────────────────┐
│ Late 2025: Expiration of severe US sanctions; Merey crude begins recovery│
└───────────────────────────────────┬────────────────────────────────────┘
                                    ▼
┌────────────────────────────────────────────────────────────────────────┐
│ Jan 2026: Capture of Nicolas Maduro; US launches stabilization plan    │
└───────────────────────────────────┬────────────────────────────────────┘
                                    ▼
┌────────────────────────────────────────────────────────────────────────┐
│ Feb 2026: Outbreak of US-Iran War; global shipping attacks commence    │
└───────────────────────────────────┬────────────────────────────────────┘
                                    ▼
┌────────────────────────────────────────────────────────────────────────┐
│ Mar-Jul 2026: Vitol & Trafigura consolidate control over 50%+ of exports│
└───────────────────────────────────┬────────────────────────────────────┘
                                    ▼
┌────────────────────────────────────────────────────────────────────────┐
│ Aug 2026: Freight rates hit record highs; traders demand $20 discounts  │
└────────────────────────────────────────────────────────────────────────┘
The Late 2025 Sanctions Wind-Down
By the final quarter of 2025, the strict sanctions regime imposed by Washington on PDVSA began to unravel. As the U.S. government sought alternative crude sources to stabilize domestic retail gasoline prices, it permitted a broader array of international buyers, vessel owners, and trading houses to re-engage with Venezuela.
During this period, punitive clauses—such as high-risk premiums for loading at security-compromised South American ports—began to disappear from charter party agreements. Large, reputable vessel owners returned to Venezuelan waters, bringing shipping costs down to market standards. This normalization allowed Venezuela’s heavy, sour Merey crude to steadily recover from the steep discounts of previous years, narrowing its price gap relative to international benchmarks.
January 2026: The Capture of Maduro and the U.S. Re-engagement
The geopolitical landscape shifted dramatically in January 2026 when U.S. forces captured Venezuelan President Nicolás Maduro. In the ensuing political transition, Washington immediately moved to reactivate Venezuela’s energy infrastructure. The goal was clear: unlock the country’s vast oil reserves—the largest in the world—to offset tightening global supplies.
Taking advantage of the sudden opening, Vitol and Trafigura positioned themselves as the primary intermediaries. They secured long-term off-take agreements, effectively sidelining smaller, opaque trading entities that had dominated Venezuelan oil marketing during the sanctions era.
February 2026: The Outbreak of the U.S.-Iran War
The optimism surrounding Venezuela’s oil revival was short-lived. In late February 2026, long-simmering tensions boiled over into a direct military conflict between the United States and Iran. The outbreak of the U.S.-Iran war triggered the largest wave of attacks on commercial shipping since World War II.
Drone strikes, missile attacks, and naval blockades in the Middle East disrupted critical maritime chokepoints, including the Strait of Hormuz and the Red Sea. The immediate fallout was a global scramble for secure tanker capacity. Fleet operators diverted vessels to longer, safer routes, which reduced available tonnage and caused global chartering rates to skyrocket.
August 2026: The Freight Crisis Collides with Export Ambitions
By August 2026, the global shipping crisis had reached Venezuela’s primary export terminal in Jose. Despite stable production, Venezuela’s oil exports plateaued at 1.17 million bpd, capped by infrastructure bottlenecks and a shortage of affordable tankers.
With the cost of moving crude to the U.S. Gulf Coast and Europe rising sharply, Vitol and Trafigura began formal negotiations with PDVSA. They sought to adjust pricing formulas to reflect the new logistical realities, bringing the current standoff to a head.
Supporting Context & Metrics: The Broken Economics of Venezuelan Logistics
The negotiations between international trading houses and PDVSA are governed by a stark financial reality: when freight rates rise, the free-on-board (FOB) value of crude oil at the port of origin must fall if the delivered price is to remain competitive at global refining hubs.
AFRAMAX TANKER CHARTERING COSTS
(Jose, Venezuela to US Gulf Coast - 700,000 bbl capacity)

January 2026:
[$$$] $1.35 Million total ($1.90 per barrel)

August 2026:
[$$$$$$$$] $3.50 Million total ($5.00 per barrel)
The Aframax Surge: Demystifying the Freight Math
The primary vessel utilized for regional crude transport in the Caribbean and Gulf of Mexico is the Aframax tanker, capable of carrying approximately 700,000 barrels of crude. Data from maritime intelligence firm Signal Maritime illustrates the scale of the freight rate surge:
- January 2026: Chartering an Aframax from the Venezuelan port of Jose to the U.S. Gulf Coast cost approximately $1.35 million, translating to a transport cost of $1.90 per barrel.
- August 2026: The cost for the same voyage surged to $3.5 million, or roughly $5.00 per barrel.
This $3.10-per-barrel increase in shipping costs directly eats into the margins of intermediaries. Because Gulf Coast refiners can source similar heavy, sour grades domestically or from Canada without incurring these high ocean-freight premiums, they refuse to absorb the shipping costs for Venezuelan crude. Consequently, the transport premium must be deducted from the price paid to PDVSA at the loading port.
THE INTERMEDIARY SQUEEZE
Illustrative pricing math for a barrel of Merey crude (USD per barrel)

  $90.00  (Assumed Brent Benchmark Price)
- $14.00  (Standard August Merey Discount)
────────
  $76.00  (Delivered Price Target at US Refineries)
-  $5.00  (August Freight Cost to US Gulf Coast)
-  $2.00  (Trader's Required Margin & Risk Premium)
────────
  $69.00  (Implied FOB Value at Port of Jose)

==> To achieve this FOB value, the purchase discount relative to Brent
    must widen to $21.00 per barrel.
Price Formula Disconnects: Merey vs. Brent
The official pricing formula for Venezuela’s Merey crude has failed to keep pace with these shifting shipping costs. According to figures reported by Venezuela to OPEC:
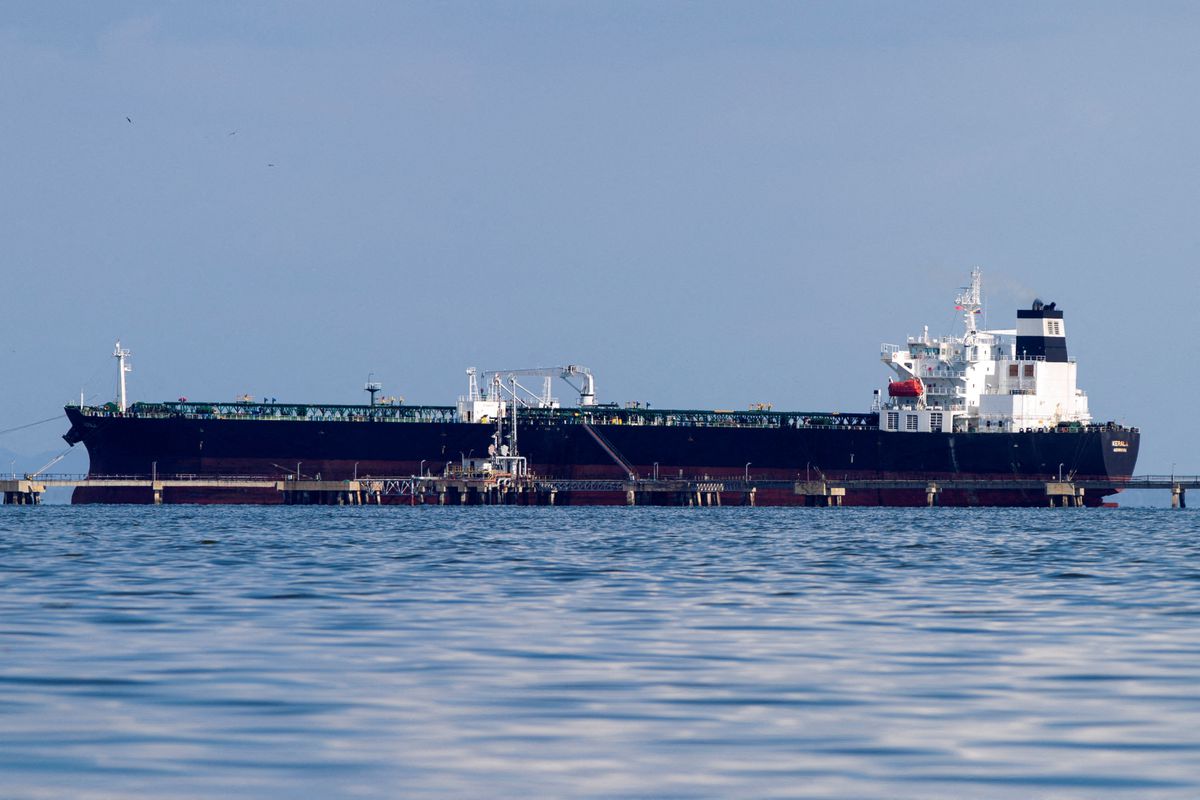
- The official formula price for Merey crude rose to $76.82 per barrel in August, up from $67.36 in July.
- This official price represented a discount of roughly $14.00 per barrel below the international Brent benchmark.
While PDVSA has managed to agree on discounts of $12.00 to $13.00 per barrel with its direct joint-venture partners (such as European and American majors holding equity stakes in local projects), those partners are finding the crude impossible to market at those levels. To move the oil, joint-venture partners have been forced to resell their allocations to intermediaries at a $16.00-per-barrel discount.
Recognizing that even a $16.00 discount is insufficient to cover current freight rates, Vitol and Trafigura are bidding $18.00 to $20.00 below Brent for cargoes destined for the U.S. or Europe.
Infrastructure Congestion and Export Plateaus
Compounding the pricing crisis is the physical deterioration of Venezuela’s port infrastructure. Decades of underinvestment, combined with the sudden rush of post-sanctions traffic, have created severe congestion.
VENEZUELAN EXPORT STAGNATION (AUGUST 2026)

Total Country Exports:       1.17 Million bpd (Unchanged from July)
Vitol & Trafigura Volume:    597,000 bpd (Down slightly from 604,000 bpd in July)
Tanker Waiting Times:        At highest levels since January 2026
The inability of the Jose terminal to efficiently load larger Suezmax or Very Large Crude Carriers (VLCCs)—which offer better economies of scale than Aframaxes—prevents traders from lowering their per-barrel transport costs. As a result, tankers face lengthy delays, racking up expensive demurrage fees that further erode the economics of Venezuelan crude.
Official Positions and Market Reactions
The ongoing negotiations are characterized by a quiet but intense battle for leverage, with each party attempting to protect its balance sheet from the realities of the wartime shipping market.
Trading Houses Keep Silent
Both Vitol and Trafigura have declined to comment publicly on their pricing strategies or the progress of their negotiations with PDVSA. This silence is standard practice for the fiercely competitive commodity trading sector, where revealing pricing formulas or bidding strategies can quickly compromise market position.
Privately, however, trading sources confirm that the high cost of shipping has made Venezuelan crude a difficult sell. "Freight is a huge issue," noted one trading source directly involved in the Caribbean market. "Refiners simply don’t want it at the price it’s costing us to deliver. If PDVSA won’t adjust its pricing, the oil will simply sit in storage."
PDVSA’s Direct-Sales Gambit
PDVSA, which did not respond to requests for comment, is facing a severe cash-flow squeeze. Under pressure from the Venezuelan transition government to generate immediate revenue for national reconstruction, the state oil firm is resistant to granting the $18-to-$20 discounts demanded by Vitol and Trafigura.
To counter the traders’ leverage, PDVSA has recently attempted to bypass intermediaries entirely. The state company is trying to sell cargoes directly to end-user refineries in the U.S. Gulf Coast and Europe.
However, industry analysts point out that this direct-sales strategy faces significant hurdles. Most major refiners prefer the logistical flexibility and credit terms offered by large trading houses like Vitol and Trafigura. Furthermore, many compliance departments remain hesitant to clear direct financial transactions with PDVSA, preferring the buffer of an international intermediary.
Future Outlook: Geopolitical Crossroads and Energy Security
The resolution of the pricing dispute between PDVSA and the major trading houses will have significant implications for both global oil flows and the political stabilization of Venezuela.
THE COLD WAR FOR OIL MARGINS: KEY VARIABLES TO WATCH

 ┌──────────────────────────────┐     ┌──────────────────────────────┐
 │     Global Freight Rates     │     │     PDVSA Infrastructure     │
 ├──────────────────────────────┤     ├──────────────────────────────┤
 │ If U.S.-Iran war escalates,  │     │ Without capital upgrades to  │
 │ freight rates will rise,     │     │ loading terminals, export    │
 │ forcing deeper discounts.    │     │ volumes will remain capped.  │
 └──────────────┬───────────────┘     └──────────────┬───────────────┘
                └──────────────┬─────────────┘
                               ▼
 ┌───────────────────────────────────────────────────────────┐
 │                    Market Equilibrium                     │
 │      Will PDVSA capitulate to $20/bbl discounts,          │
 │      or will Venezuelan oil accumulate in storage?        │
 └───────────────────────────────────────────────────────────┘
Can the U.S. Stabilization Plan Survive the Shipping Crisis?
The primary casualty of the freight crisis may be Washington’s plan to rapidly increase Venezuelan oil exports to offset the loss of Middle Eastern barrels. If Vitol and Trafigura cannot secure the discounts needed to make shipments profitable, they may reduce their chartering activity in Venezuela. This would lead to a buildup of domestic inventories, eventually forcing PDVSA to shut in production.
For the U.S. administration, which had hoped a post-Maduro Venezuela would quickly bring stable volumes to market, the shipping crisis serves as a reminder of the vulnerabilities inherent in maritime supply chains during times of war.
Long-Term Infrastructure Demands
Even if the geopolitical situation in the Middle East stabilizes and freight rates return to normal, Venezuela’s energy sector cannot reach its full potential without massive capital investment. The country’s export terminals require dredging to accommodate larger vessels, and its blending facilities need modern equipment to process heavy Orinoco crude into exportable grades.
In the medium term, PDVSA may have no choice but to yield to the terms set by Vitol and Trafigura. As long as global shipping remains a high-risk, high-cost endeavor, the trading houses hold the upper hand. They possess the liquidity, the fleets, and the risk tolerance required to move Venezuela’s oil, giving them the leverage to demand a steep price for their services.