
Executive Overview
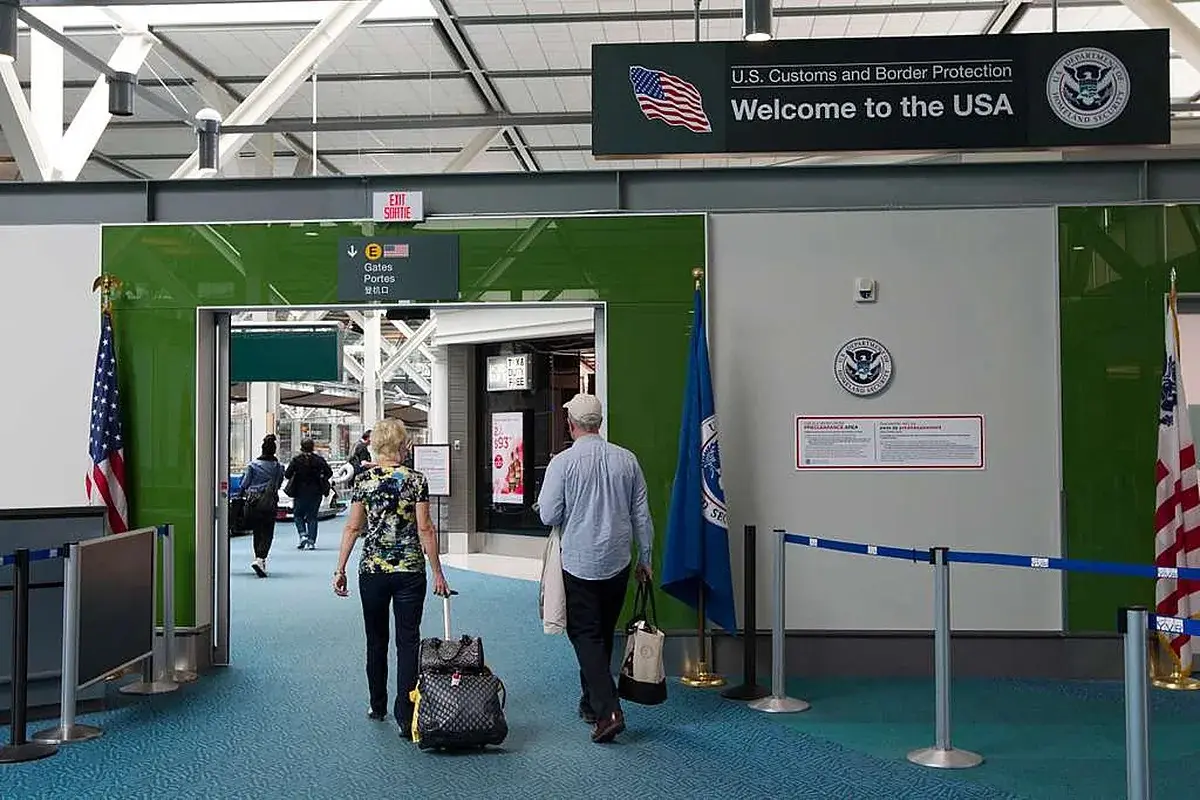
The cross-border travel corridor connecting Canada and the United States has long been celebrated as one of the most dynamic, economically integrated, and heavily trafficked bilateral relationships in global tourism. Millions of travelers cross the 49th parallel annually for leisure, business, family visits, and shopping, generating billions of dollars in economic activity for both nations.
However, recent data released by Statistics Canada reveals a complex and sobering reality for the tourism and aviation sectors: while Canadian travelers are indeed returning to the United States, the trajectory of this recovery is slow, uneven, and far from complete.
According to figures published on Tuesday by Statistics Canada, Canadian-resident return trips from the U.S. rose by 6.8% in September compared to the same month in the previous year. This metric marks the sixth consecutive month of year-over-year growth, signaling sustained momentum in cross-border mobility. A deeper dive into the numbers shows that both primary modes of transit experienced gains, with return trips by car increasing by 5.6% and air travel jumping by a more robust 11.6%.
Yet, celebrating these consecutive months of marginal growth masks a deeper structural deficit. When stacked against pre-downturn benchmarks from 2024, the modern landscape of cross-border movement paints a starkly different picture. In September, return trips from the U.S. by car languished at levels 31.1% lower than those recorded in September 2024. Meanwhile, air travel returns remained depressed by 18.7% over the same baseline.
This juxtaposition—steady month-over-month recovery weighed down by a yawning chasm from historical norms—captures the current predicament of North American tourism. Industry stakeholders, macroeconomic analysts, and government officials are left grappling with a fundamental question: Why is the normalization of Canadian travel to the United States taking significantly longer than anticipated, and what structural shifts are altering the fabric of North American cross-border behavior?
Detailed Chronology: Tracking the Post-Downturn Trajectory
To understand the current state of Canadian travel to the United States, it is essential to trace the timeline of events, economic pressures, and consumer confidence shifts that have shaped the market since the baseline highs of 2024.
The 2024 Baseline and Subsequent Shock
In 2024, cross-border travel between Canada and the U.S. appeared to be operating on a standard post-pandemic recovery curve. Pent-up demand for travel, strong consumer balance sheets, and relatively stable currency exchanges supported high volumes of leisure and business trips. Highways connecting Ontario to New York and Michigan, as well as Western Canadian crossings into Washington and Montana, buzzed with traffic. Major aviation hubs like Toronto Pearson, Vancouver International, and Montréal-Trudeau processed record volumes of U.S.-bound passengers.
However, as the calendar turned, a confluence of macroeconomic headwinds began to take a heavy toll. Persistent inflationary pressures, fluctuating currency valuations, and escalating costs of living began to squeeze discretionary household budgets across Canada. The cost of lodging, dining, and entertainment within major American metropolitan areas surged, rendering cross-border travel markedly more expensive for Canadians trading in Canadian dollars.
The Turning Point: Spring 2025 to Early 2026
The downward spiral in travel volume bottomed out during late 2024 and early 2025, setting the stage for what would become a protracted period of stagnation. During this window, cross-border shopping—historically a cornerstone of Canadian weekend trips to border states like Washington, New York, and North Dakota—plummeted.
It was not until the spring of 2025 that the first tentative signs of stabilization emerged. Industry analysts noted that Canadian consumers were beginning to re-engage with the U.S. market, albeit with heightened price sensitivity and shorter itineraries.
The Six-Month Growth Streak (Mid-2025 to September 2026)
The recent Statistics Canada report highlights a critical milestone: a six-month consecutive streak of year-over-year growth spanning from spring through September 2026.
- April through June 2026: Initial green shoots appeared as early spring weather encouraged regional driving trips, while airlines reported incremental capacity restorations on transborder routes.
- July and August 2026: The traditional summer peak season brought higher absolute numbers of travelers, though volume caps remained well below 2024 peaks. Families prioritized essential holiday travel over luxury or multi-destination U.S. trips.
- September 2026: The latest data release showing the 6.8% overall increase confirms that the recovery has successfully transitioned from a summer anomaly into a persistent trend. Nevertheless, the stubborn double-digit deficits compared to September 2024 underscore that "growth" in this context is merely a slow climb out of a deep valley.
Supporting Context & Metrics: Analyzing the Data
A granular examination of the Statistics Canada metrics illuminates the underlying mechanics of how Canadians are currently interacting with the U.S. travel market.
The Modal Split: Cars vs. Airplanes
The divergence in recovery rates between automobile travel and air travel reveals distinct consumer behaviors and economic constraints:
| Mode of Transport | Sept 2026 YoY Growth | Deficit vs. Sept 2024 Baseline |
|---|---|---|
| Automobile Travel | +5.6% | -31.1% |
| Air Travel | +11.6% | -18.7% |
| Total Return Trips | +6.8% | N/A |
- The Automobile Lag (-31.1%): The severe lag in road-based border crossings is perhaps the most telling indicator of changing consumer habits. Historically, driving across the border for a weekend getaway, a sporting event, or a shopping trip was an affordable, spontaneous activity for middle-class Canadian families. Today, the 31.1% deficit points to structural deterrents. Beyond the persistent weakness of the Canadian dollar against the greenback, the cost of fuel, cross-border auto insurance adjustments, and the sheer expense of American gas stations, hotels, and restaurants have fundamentally altered the value proposition of a quick weekend drive south.
- The Air Travel Resilience (-18.7%): While air travel is also severely depressed compared to 2024 levels, its year-over-year growth rate (+11.6%) outpaces that of driving. This suggests that the demographic driving current U.S. travel is skewed toward higher-income households or corporate travelers whose needs are less elastic in the face of inflation. Business travelers, snowbirds securing long-term winter rentals in Florida or Arizona, and travelers visiting distant family members are more likely to absorb higher costs and fly rather than drive.
Macroeconomic Factors at Play
Several external forces continue to dictate the pace of this recovery:
- The Exchange Rate: The persistent disparity between the Canadian dollar (CAD) and the U.S. dollar (USD) acts as an automatic tax on Canadian travelers. Every transaction south of the border requires a conversion penalty that makes U.S. goods and services roughly 30 to 35% more expensive before local taxes and tips are even factored in.
- Domestic Tourism Incentives: Faced with expensive alternatives abroad, many Canadian households have pivoted toward domestic travel or international destinations outside the United States where exchange rates or local cost-of-living metrics offer superior value.
- Consumer Sentiment and Economic Uncertainty: Ongoing anxieties regarding employment stability, mortgage renewals at higher interest rates, and overall household debt have made Canadians exceptionally cautious discretionary spenders.
Official Statements and Industry Perspectives
The release of the latest Statistics Canada data has triggered widespread commentary from tourism boards, aviation executives, and economic analysts across North America.
Industry Reactions
Representatives from the Tourism Industry Association of Canada (TIAC) have expressed cautious optimism regarding the six-month streak of positive year-over-year metrics.
"We are witnessing the resilience of the Canadian traveler," notes a senior policy analyst at TIAC. "Despite facing significant financial headwinds, Canadians continue to prioritize cross-border connection. However, we must remain clear-eyed: a 6.8% monthly bump does not mean the sector has recovered. We are climbing out of a very deep hole, and the structural costs of traveling to the United States remain a formidable barrier for the average household."
Aviation sector leaders echo these sentiments, pointing out that airline seat capacity between Canada and the U.S. has been carefully managed to match subdued demand.
"Airlines have rationalized their transborder networks over the past two years," explains an executive at a major Canadian carrier. "While an 11.6% increase in air return trips is a welcome sign of life, carriers are not rushing to flood the market with cheap seats. Yield management and profitability remain the priority until macroeconomic conditions stabilize."
Retail and Hospitality Concerns on Both Sides of the Border
U.S. border states—particularly Washington, Montana, New York, and Vermont—have historically relied heavily on Canadian day-trippers and weekend shoppers to sustain local retail economies, outlet malls, and hospitality sectors. Chambers of commerce in these regions have reported prolonged sluggishness in foot traffic.
Conversely, traditional Canadian snowbird destinations, such as Florida and Arizona, are observing a more resilient cohort of long-stay visitors. While overall headcounts are down compared to the record highs of 2024, those who do make the annual migration are tending to stay for the duration of the winter season, offsetting some of the losses through higher individual expenditures.
Future Outlook: What Lies Ahead for the Cross-Border Corridor?
As the industry looks past the current autumn season and toward the critical winter holiday and snowbird migration periods, forecasters are attempting to map the future of Canadian travel to the United States.
Key Catalysts for Further Recovery
- Currency Stabilization: Any meaningful strengthening of the Canadian dollar against the greenback would instantly unlock pent-up demand, transforming the calculus of cross-border shopping and leisure travel.
- Inflation Relief and Wage Growth: As domestic inflationary pressures ease and real wages catch up to cumulative price increases, discretionary household budgets are expected to loosen, enabling more middle-class families to resume regular U.S. travel habits.
- Corporate Travel Evolution: The corporate sector continues to redefine its travel policies. As cross-border business meetings, conferences, and project visits normalize, the air travel segment is positioned to claw back further ground toward its 2024 benchmarks.
Long-Term Structural Shifts
Industry experts caution that the market may never fully revert to the exact patterns of 2024. Consumer behaviors forged during periods of high economic stress—such as a permanent preference for domestic destinations, increased utilization of digital and remote communication technologies for business, and heightened price consciousness—are likely to leave permanent footprints on the cross-border ecosystem.
In conclusion, while the six consecutive months of year-over-year growth reported by Statistics Canada provide a welcome narrative of recovery, the monumental gaps remaining against 2024 benchmarks serve as a reminder of the fragility of modern tourism. The road back to pre-downturn normalcy is long, winding, and dependent on a delicate alignment of macroeconomic stability, currency health, and shifting consumer confidence across the 49th parallel.