
Executive Overview
The global travel and tourism economy has spent the better part of the post-pandemic era charting a course toward resilient, sustained recovery. Yet, as the latest data from the Skift Travel Health Index indicates, the path forward remains highly susceptible to exogenous shocks. For July, the global index stood at 99—marking a marginal 1% year-on-year contraction. While a single-digit global dip might suggest a plateauing market, a deeper examination of regional dynamics reveals a starkly fractured landscape.
Nowhere was this fracture more pronounced than in the Middle East and Africa (MEA). Having reached a major milestone in June—fully recovering to the pre-pandemic benchmark level of 100—the region suffered a sharp, unexpected pullback in July, plummeting to 94. This sudden reversal underscores the extreme fragility of traveler confidence in emerging and geopolitically sensitive corridors.
The primary catalysts behind this contraction are multifaceted, driven by a resurgence of regional security concerns, cascading travel advisories issued by major source markets, and widespread flight suspensions. These disruptions collided with underlying market weaknesses that had been brewing for months, effectively paralyzing the conversion pipeline. Travelers who had expressed preliminary interest in regional destinations ultimately hesitated, resulting in canceled itineraries and stagnant booking curves.
Amid this broader regional retrenchment, however, pockets of resilience emerged. Most notably, the vacation rentals sector outperformed all other tourism verticals in the MEA, surging 14% year-on-year. This dichotomy points to a shifting consumer preference: as traditional hospitality formats—such as hotels and international carriers—absorb the brunt of security-related cancellations, alternative accommodations are proving uniquely adaptable to shifting risk tolerances.
As industry analysts sound the alarm over what could potentially become a "lost year" for Gulf tourism and broader regional inbound travel, stakeholders are forced to re-evaluate risk-management frameworks, marketing strategies, and operational agility. This report provides a comprehensive analysis of the July data, tracing the chronological sequence of events, examining key performance metrics, integrating industry perspectives, and forecasting the long-term trajectory of travel health across the Middle East and Africa.
Detailed Chronology of the July Downturn
To fully understand the severity of the July contraction in the Middle East and Africa, it is essential to trace the chronological sequence of events that transformed a recovering marketplace into a landscape of hesitation and stasis. The shift from June’s optimism to July’s pessimism was swift, catalyzed by a confluence of geopolitical friction and operational bottlenecks.
Q2 Momentum and the June Benchmark Peak
Entering the second quarter of the year, the Middle East and Africa travel sector had demonstrated remarkable tenacity. Fueled by aggressive tourism diversification strategies in the Gulf Cooperation Council (GCC) states, aggressive air-route expansions, and robust intra-regional demand, the market steadily closed the gap with its pre-pandemic performance baselines.
By June, these tailwinds culminated in a significant psychological and statistical milestone: the Skift Travel Health Index for the MEA region hit 100. Hoteliers, airline executives, and destination management organizations (DMOs) celebrated the return to baseline parity. Forward-looking booking indicators for the summer peak season appeared robust, and marketing campaigns aimed at attracting long-haul travelers from Europe, Asia, and the Americas were operating at full throttle. Industry stakeholders anticipated a lucrative summer characterized by high occupancy rates and strong yield management.
The July Inflection Point: Security Realities and Advisories
The trajectory shifted dramatically in the opening weeks of July. A flare-up in regional geopolitical tensions sent immediate shockwaves through international diplomatic and intelligence communities. Governments across key inbound source markets—including the United Kingdom, the United States, and several European Union member states—rapidly updated their travel advisories for parts of the Middle East.
While these advisories often targeted specific sub-regions or zones of active friction, the psychological contagion effect proved systemic. Consumers in Western source markets frequently conflate localized security events with region-wide instability. Consequently, consumer perception outpaced on-the-ground reality, creating a wave of generalized apprehension.
Flight Suspensions and Operational Bottlenecks
Compounding the impact of updated travel advisories, major international carriers began implementing proactive flight suspensions and reroutings to avoid perceived airspace risks. The sudden reduction in airlift capacity acted as an immediate deterrent for international travelers.
When airlines ground routes or modify flight paths, the downstream effects on tourism are instantaneous:
- Connectivity Deficits: Multi-leg journeys become prohibitively complex or expensive.
- Consumer Anxiety: The visible withdrawal of major carriers serves as a powerful psychological signal of instability, validating fears sparked by government advisories.
- Corporate Travel Freezes: Multinational corporations and travel management companies (TMCs) automatically trigger duty-of-care protocols, banning non-essential business travel to affected corridors.
The Conversion Bottleneck
By mid-July, the structural impact of these developments became glaringly apparent in the conversion metrics. While top-of-funnel digital engagement—such as destination searches, website traffic to tourism boards, and preliminary flight inquiries—remained surprisingly stable, the transition from interest to action ground to a halt.
Travelers were actively researching vacations and business trips to the region, but when presented with the final booking screen, hesitation took over. Fear of sudden cancellations, uninsurable trip disruptions, or escalating security concerns caused conversion rates to plummet. By the close of July, the index score of 94 painted a clear picture of a market constrained not by a lack of fundamental appeal, but by an acute crisis of traveler confidence.
Supporting Context & Metrics
Quantitative analysis of the Skift Travel Health Index reveals deeper structural nuances within the July dataset. While the global index held relatively steady at 99 (down 1% year-on-year), the regional variance highlights the disparate realities facing different global travel economies.
Global vs. Regional Index Performance
| Region / Metric | Index Score (July) | Year-on-Year Change | Trend Direction |
|---|---|---|---|
| Global Travel Health Index | 99 | -1% | Stable / Minor Contraction |
| Middle East & Africa (June) | 100 | Baseline Recovery | Peak Performance |
| Middle East & Africa (July) | 94 | Significant Drop | Sharp Pullback |
| MEA Vacation Rentals Sector | Benchmark +14% | +14% vs. Prior Year | Outperforming Growth |
The Gulf Tourism Paradox: A Potential "Lost Year"?
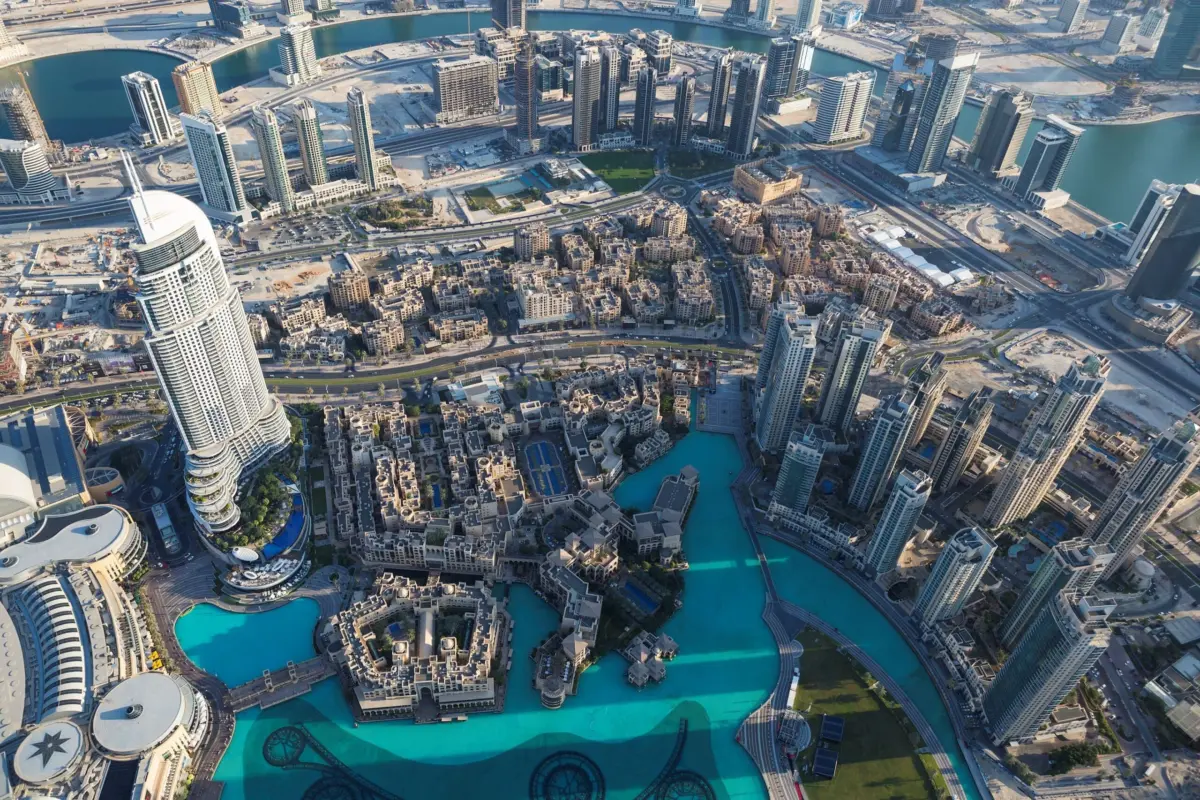
Recent reporting has increasingly focused on the vulnerability of the Gulf tourism economy. For years, nations within the GCC—led by the United Arab Emirates, Saudi Arabia, Qatar, and Oman—have poured billions of dollars into transforming their economies away from hydrocarbon dependence and toward world-class tourism, entertainment, and mega-events.
Massive infrastructure projects, luxury hospitality developments, and aggressive sports diplomacy (including global soccer tournaments, Formula 1 grands prix, and high-profile golf circuits) have successfully positioned the Gulf as a premier global tourism hub. However, these investments rely heavily on uninterrupted global mobility and absolute geopolitical stability.
When regional security crises erupt, the heavy reliance on long-haul inbound transit makes Gulf destinations exceptionally sensitive. The recent data suggests that the momentum built over previous quarters risks being severely blunted. Industry analysts are increasingly whispering about a potential "lost year" for Gulf tourism growth—not because infrastructure is lacking or demand is structurally dead, but because the frequency of external shocks prevents the market from sustaining an uninterrupted upward trajectory.
The Bright Spot: Vacation Rentals Defy the Downtrend
Amid the broader contraction across traditional hotel inventories and legacy airline networks, the vacation rentals sector in the Middle East and Africa demonstrated remarkable decoupling. Recording a 14% year-on-year gain above the benchmark, alternative accommodations proved to be the primary structural savior for the region’s July tourism economy.
Several key factors explain this outperformance:
- Perceived Privacy and Control: Travelers navigating security uncertainties often prefer self-contained accommodations over large, high-profile international hotel complexes, which are sometimes viewed as more visible targets for security incidents.
- Domestic and Intra-Regional Travel: As international long-haul arrivals contracted, domestic travelers and regional expatriates stepped in to fill the void. This demographic heavily favors vacation rentals for weekend getaways, family staycations, and flexible holiday arrangements.
- Agility of Supply: Unlike massive hotel developments that require sustained corporate travel or large tour groups to maintain high occupancy, vacation rental portfolios can pivot quickly to capture micro-trends, offering flexible cancellation policies that reassure hesitant bookers.
Official Statements and Industry Perspectives
The sudden contraction recorded in the July index has triggered intense debate among tourism ministers, airline executives, and hospitality leaders across the Middle East and Africa.
Perspectives on Security and Communication
Speaking on condition of anonymity, a senior executive at a major Middle Eastern hotel conglomerate addressed the communication challenge facing regional DMOs:
"The challenge we face is not the reality on the ground in our specific destinations, but the broad-brush narrative painted by international travel advisories. When a security incident occurs in one corner of a massive region, source markets often react as if the entire geographical landmass is compromised. Our primary task right now is proactive, transparent communication—reassuring travelers that our cities remain safe, operational, and welcoming."
This sentiment is echoed by regional aviation analysts who have pointed to the speed of flight suspensions as a destabilizing factor. While airlines must prioritize passenger safety, premature or blanket suspensions can exacerbate panic.
Strategic Pivots by Tourism Boards
In response to the July data, several tourism boards across the MEA have initiated emergency strategic reviews. Rather than investing heavily in expensive top-of-funnel campaigns in markets severely impacted by negative travel advisories, DMOs are redirecting marketing spend toward:
- Intra-Regional Source Markets: Encouraging travel from neighboring nations within Africa and the GCC where travelers possess a more nuanced understanding of local security dynamics.
- Resilience Messaging: Highlighting safety records, advanced infrastructure, and flexible booking guarantees.
- Niche Tourism Verticals: Leaning into wellness, adventure, and domestic-driven vacation rental stays that have proven immune to broader macroeconomic and geopolitical jitters.
Future Outlook: Navigating the Road Ahead
As the travel industry looks past the summer peak and toward the final quarters of the year, the outlook for the Middle East and Africa remains cautiously nuanced. The index score of 94 in July serves as a sobering reminder that recovery is never a linear progression.
Short-Term Stabilization Strategies
To reverse the downward pressure observed in July, industry stakeholders must execute a coordinated multi-pronged strategy over the coming months:
- Restoring Airlift Confidence: Tourism authorities must work in close collaboration with international civil aviation authorities and carrier networks to ensure that flight suspensions are lifted as soon as security conditions normalize, re-establishing vital air bridges.
- Enhanced Risk-Mitigation Marketing: Hospitality providers must continue offering hyper-flexible booking and cancellation terms. Lowering the financial risk of booking a trip is one of the most effective ways to convert hesitant online lookers into confirmed guests.
- Targeting Resilient Demographics: Doubling down on domestic tourism, regional GCC travel, and alternative accommodation formats will provide a reliable revenue cushion while long-haul international markets recalibrate their risk assessments.
Long-Term Structural Resilience
Looking toward the medium and long term, the foundational drivers of travel to the Middle East and Africa remain intact. The region’s ongoing diversification megaprojects, massive investments in aviation hubs, and expanding cultural offerings ensure its enduring appeal on the global stage.
However, the events of July have reinforced a vital lesson for the regional tourism economy: true resilience requires diversification not only of economic product, but of source markets and risk-management strategies. By acknowledging the fragility of traveler confidence and building operational frameworks capable of absorbing geopolitical shocks, the Middle East and Africa travel sector can transform temporary volatility into a catalyst for enduring maturity.