
Executive Overview
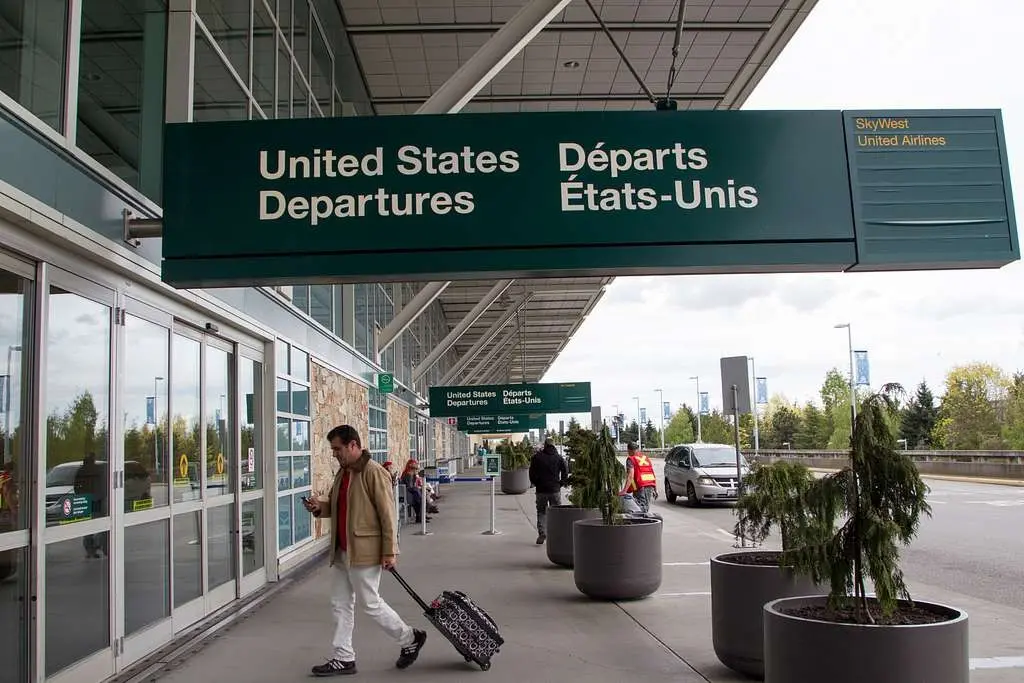
In the intricate dance of international economics and geopolitics, cross-border tourism often serves as an immediate barometer of bilateral relations. For months, tourism boards, hospitality executives, and retail leaders across the United States held their collective breath. As political rhetoric sharpened and the specter of an escalating trade war between Washington and Ottawa loomed large, industry insiders predicted a chilling effect on what had been a fragile, budding rebound in Canadian travel to the United States.
Conventional economic wisdom suggested that deteriorating trade relations, combined with tariff threats and heightened nationalistic sentiments, would deter Canadian neighbors from crossing the southern border for vacations, shopping trips, and business ventures. However, recent hard data has defied these gloomy prognostications.
According to figures released on Friday by Statistics Canada—the national statistical agency tracking return trips from the U.S. by Canadian residents—travel surged by an impressive 8.8% in August. This marks the fifth consecutive month of year-over-year growth, signaling unexpected resilience in one of the most vital feeder markets for the American tourism industry.
While the headline-grabbing 8.8% increase offers a much-needed shot of optimism for U.S. hospitality providers, a deeper analytical dive reveals a more nuanced and complex landscape. Travel volumes are indeed rebounding, propelled by robust increases in both automobile and air travel. Yet, the industry remains far from the pre-crisis highs of 2024. Economists and statisticians are quick to point out that these consecutive months of growth are heavily influenced by a "base-year effect"—a statistical phenomenon where sharp percentage gains appear dramatic simply because they are bouncing off profoundly depressed historical lows.
This comprehensive report delves into the mechanics of this cross-border travel revival. We examine the chronological trajectory of U.S.-Canada travel trends, parse the intricate metrics surrounding automobile and air transport, analyze official statements from statistical and tourism authorities, and assess the broader economic and political outlook for the remainder of 2025 and beyond.
Detailed Chronology: The Evolution of U.S.-Canada Travel in 2025
To fully understand the significance of August’s 8.8% surge, it is essential to trace the turbulent timeline that defined the cross-border travel market leading up to this milestone. The relationship between Canadian travel habits and U.S. political dynamics has experienced a series of distinct phases over the past several quarters.
Early 2025: The Political Shift and Economic Uncertainty
The year 2025 began under a cloud of diplomatic friction. Starting in the first quarter, travel trends among Canadian residents began to shift noticeably alongside evolving political tensions. As discussions surrounding trade agreements grew contentious and policymakers in both nations traded barbs over tariffs and regulatory frameworks, consumer confidence on both sides of the border experienced turbulence.
For Canadian travelers, the psychological barrier to entering the U.S. market increased. Media coverage was dominated by trade disputes, and early quarterly data reflected a hesitant consumer base. Many Canadian households opted for domestic vacations or alternative international destinations, steering clear of U.S. cities that historically relied heavily on Canadian foot traffic.
Spring 2025: Bottoming Out and the "Base-Year Effect"
By the end of the first quarter and moving into the spring months, Canadian travel to the U.S. had hit a trough. The volume of visitors had plummeted to levels that alarmed regional tourism bureaus in border states like New York, Washington, Michigan, and throughout Florida and California.
It was during this period that Statistics Canada began introducing the concept of the "base-year effect" into its monthly briefings. Statisticians cautioned analysts and industry stakeholders not to over-interpret early signs of recovery as a full-scale boom. Because the baseline volume of visitors had dropped so precipitously in the preceding months, any minor influx of travelers would naturally generate high percentage increases when compared year-over-year.
Summer 2025: The Unexpected Momentum Builds
Despite the warnings regarding the base-year effect, the momentum that began to build in April and May proved remarkably persistent. Rather than stalling out after a brief seasonal bump, Canadian travel registered continuous year-over-year growth month after month.
By June and July, the travel industry began to notice tangible shifts on the ground. Hotels in border-adjacent shopping hubs reported a steady return of Canadian license plates. Airlines operating transborder routes noted incremental improvements in load factors.
August 2025: The 8.8% Surge Defies Skepticism
The culmination of this summer trend arrived with Friday’s data release from Statistics Canada. Reporting an 8.8% jump in total return trips for August, the agency confirmed the fifth straight month of positive growth. This performance decisively outperformed the cautious forecasts of many travel executives who had feared that summer trade war escalations would derail the recovery entirely.
Supporting Context & Metrics: Dissecting the August Data
While the top-line growth figure of 8.8% commands attention, a rigorous examination of the underlying metrics paints a more granular picture of how Canadians are currently experiencing travel to the United States.
Mode of Transportation: Automobile vs. Air Travel
The August data provided clear insights into how Canadians are choosing to travel south, revealing growth across both major modes of transportation, albeit at different velocities:
- Automobile Travel: Return trips by automobile registered a robust 9.9% increase in August compared to the same period in the previous year. This mode of travel is particularly crucial for regional economies in U.S. border states, driving retail sales, weekend getaways, and visits to proximity-based attractions. The strong showing in car trips suggests that short-haul leisure travel and family visits remain resilient despite economic headwinds.
- Air Travel: Return trips by air posted a more modest, yet still positive, 3.6% increase in August. While air travel recovery is typically tied to longer-haul vacations, business travel, and trips to major hubs like Florida and California, the slower growth rate compared to driving highlights consumer price sensitivity regarding airfares and foreign exchange rates.
The Long Road to Recovery: Comparing 2025 to 2024
To contextualize these recent gains, it is vital to look backward at the benchmark year of 2024. Travel executives and economists emphasize that consecutive monthly percentage increases must be measured against the significant deficits that accumulated over the past twenty-four months.
According to Statistics Canada’s comprehensive dataset, the recovery still has substantial ground to cover before returning to the baseline levels established in 2024:
- Automobile Deficit: Return trips by automobile last month remained 27.4% lower than they were two years prior. This striking double-digit gap underscores just how deep the initial contraction was and demonstrates that the current 9.9% monthly bounce is operating from a heavily diminished foundation.
- Air Travel Deficit: Similarly, return trips by air were down 22.7% compared to 2024 levels.
These comparative metrics validate Statistics Canada’s persistent warnings regarding the base-year effect. While the trajectory is undeniably upward, the destination—full recovery to pre-dispute economic and travel norms—remains a distant horizon.
| Travel Metric | August 2025 Year-over-Year Growth | Deficit Compared to 2024 Levels |
|---|---|---|
| Total Return Trips | +8.8% (5th consecutive month) | Significant overall shortfall |
| Automobile Travel | +9.9% | -27.4% lower than two years ago |
| Air Travel | +3.6% | -22.7% lower than two years ago |
Official Statements and Industry Perspectives
The dichotomy between enthusiastic monthly growth figures and sobering multi-year deficits has sparked intense debate among industry leaders, trade associations, and government statisticians.
The Trade Association Perspective
In the weeks leading up to the Statistics Canada report, major U.S. travel associations voiced deep concern over the geopolitical climate. Executives pointed out that the threat of retaliatory tariffs and hostile public discourse creates an inhospitable psychological environment for leisure travelers.
"Tourism is fundamentally built on a foundation of welcome and economic predictability," noted a senior strategist at a prominent North American travel advocacy group. "When governments engage in trade brinkmanship, consumers feel the friction. The anxiety among U.S. executives was not unfounded; historical precedent shows that trade wars quickly bleed into consumer discretionary spending, particularly cross-border travel."
Yet, following the release of the August data, industry tone has shifted toward cautious optimism mixed with pragmatic realism. While executives acknowledge that the trade tensions have not dealt a fatal blow to the market, they remain wary of declaring total victory. The underlying data proves that Canadian consumers are still exercising caution, prioritizing shorter regional driving trips over expensive long-haul flights.
Statistical Reality Checks from Ottawa
Statistics Canada has maintained a resolutely neutral, analytical stance throughout the fluctuations of 2025. In repeated monthly briefings, agency analysts have pushed back against over-enthusiastic media narratives that frame the recent monthly spikes as a miraculous economic boom.
"We must interpret these consecutive months of year-over-year growth through the proper statistical lens," an agency spokesperson reiterated following Friday’s release. "The gains observed throughout the summer are largely a function of the base-year effect. When activity contracts sharply, subsequent growth rates naturally appear magnified as the market attempts to find its footing from a severely depressed starting point."
This institutional caution serves as a necessary counterbalance to the optimism of regional tourism boards, ensuring that policymakers do not base long-term infrastructure and marketing investments on temporary statistical rebounds.
Future Outlook: Navigating Uncertainty in Late 2025 and Beyond
As the travel industry looks ahead to the final quarter of 2025 and into 2026, the trajectory of Canadian travel to the United States will depend on a delicate interplay of economic fundamentals, currency fluctuations, and, above all, political developments.
Geopolitical and Trade Trajectories
The primary variable remains the status of trade relations between Washington and Ottawa. While August data proved that individual consumers are willing to overlook macro-level political friction for the sake of vacations and family visits, any escalation into formal, damaging trade wars could introduce new shocks to the system. Tariffs that impact consumer goods, automotive manufacturing, and energy sectors inevitably filter down to household disposable income in Canada, leaving less room for discretionary cross-border travel.
Currency Valuations and Economic Fundamentals
Beyond politics, economic realities such as the exchange rate between the Canadian dollar (CAD) and the U.S. dollar (USD) will play a decisive role. A weaker Canadian dollar naturally dampens enthusiasm for U.S. travel, making hotels, dining, and entertainment significantly more expensive for Canadian tourists. Conversely, any strengthening of the loonie could provide the economic catalyst needed to close the remaining 20% to 27% deficit relative to 2024 levels.
Strategic Implications for U.S. Tourism Stakeholders
For businesses operating in the U.S. travel and hospitality sector, the path forward requires a dual strategy:
- Targeted Regional Marketing: Given that automobile travel is rebounding faster (+9.9% growth, though still down 27.4% overall), regional tourism boards in border states should continue to invest heavily in drive-market campaigns. Emphasizing short getaways, weekend shopping packages, and accessible outdoor recreation can capture the segment of Canadian travelers currently driving the recovery.
- Value Propositions for Air Travelers: With air travel lagging behind in both monthly growth (+3.6%) and multi-year recovery (-22.7%), airlines and resort operators must work collaboratively to offer competitive pricing, bundled packages, and loyalty incentives that offset currency disadvantages and encourage Canadian air travelers to return to traditional long-haul destinations.
Conclusion
The story of Canadian travel to the United States in 2025 is a testament to the resilience of human mobility in the face of political and economic headwinds. While travel executives rightfully worried that an escalating trade war would freeze cross-border tourism, the data tells a story of unexpected defiance. An 8.8% jump in August—marking five consecutive months of year-over-year growth—proves that the appetite for cross-border connection remains strong.
However, sober analysis demands that celebration be tempered with realism. With automobile and air travel still lagging 27.4% and 22.7% behind 2024 benchmarks respectively, and with Statistics Canada’s reminder of the "base-year effect," the industry is recovering rather than booming. As the political and economic landscape continues to evolve through the remainder of the year, stakeholders on both sides of the border will need to navigate this complex terrain with vigilance, adaptability, and an acute awareness of the fragile foundations upon which current gains are built.